Tag

borrowing base

11 insights

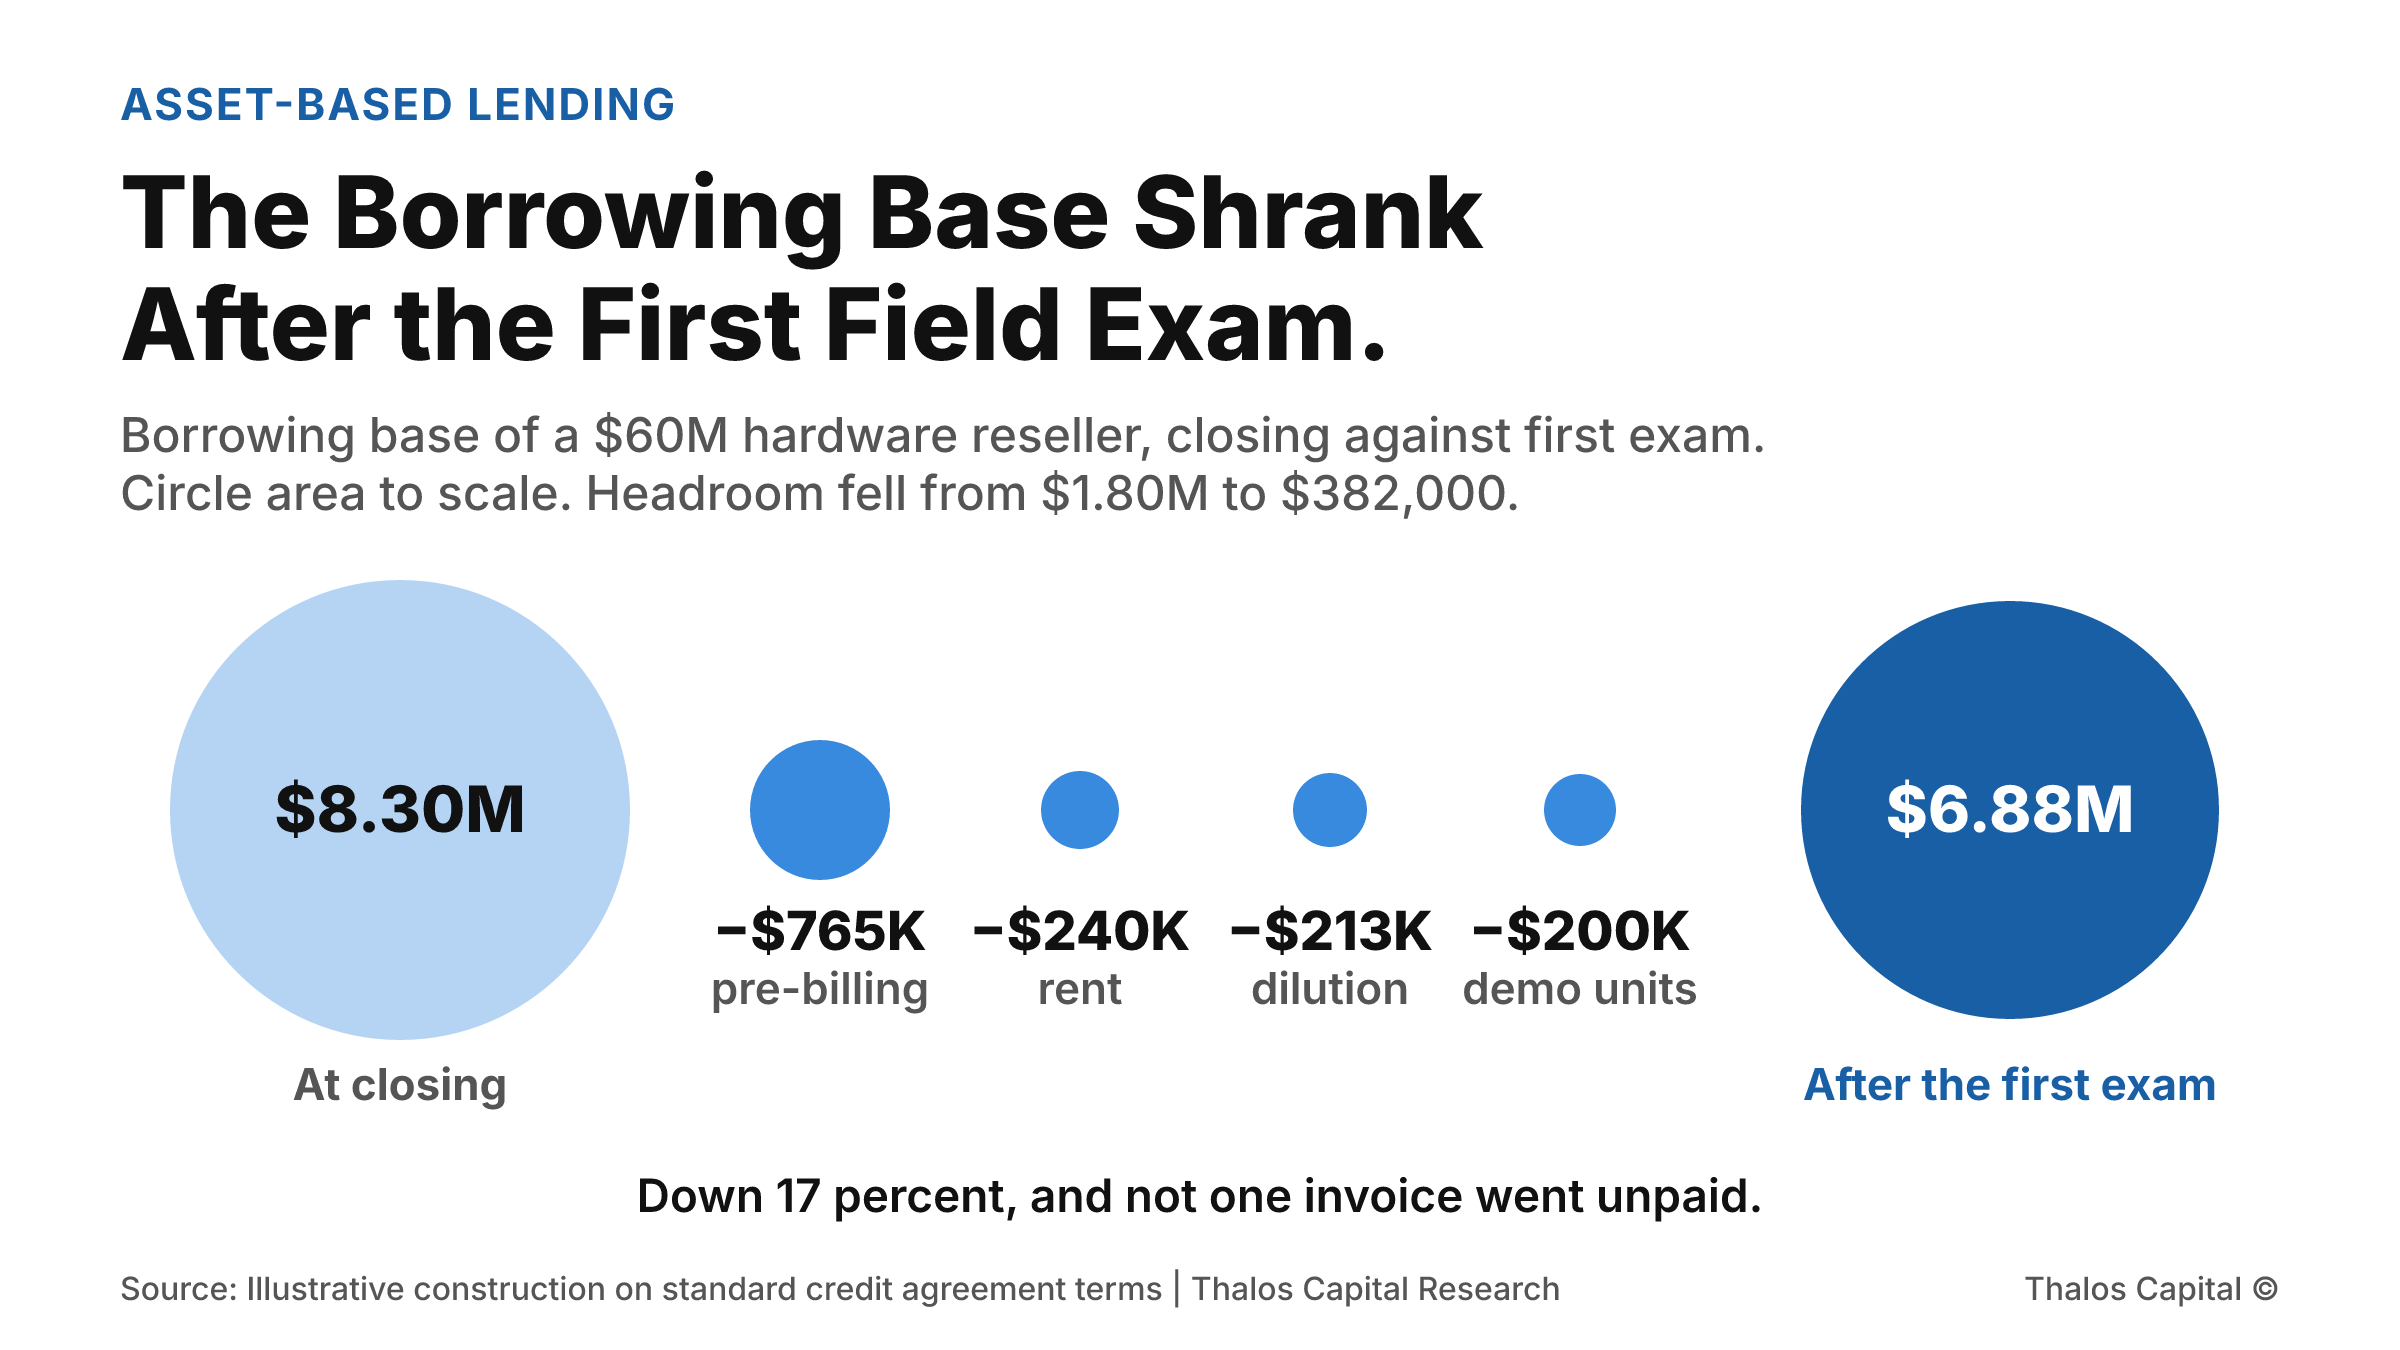
Proportional circles showing a borrowing base of $8.30 million at closing and $6.88 million after the first field exam, with four smaller circles for the adjustments between them: $765,000 of pre-billed invoices, $240,000 of rent reserve, $213,000 from excess dilution and $200,000 of demo units.

The Borrowing Base Shrank After the First Field Exam

A $60 million hardware reseller closed an asset-based line on an $8.30 million borrowing base. The first field exam tested the same collateral and found $6.88 million, and planned headroom of $1.80 million fell to $382,000.
Read More
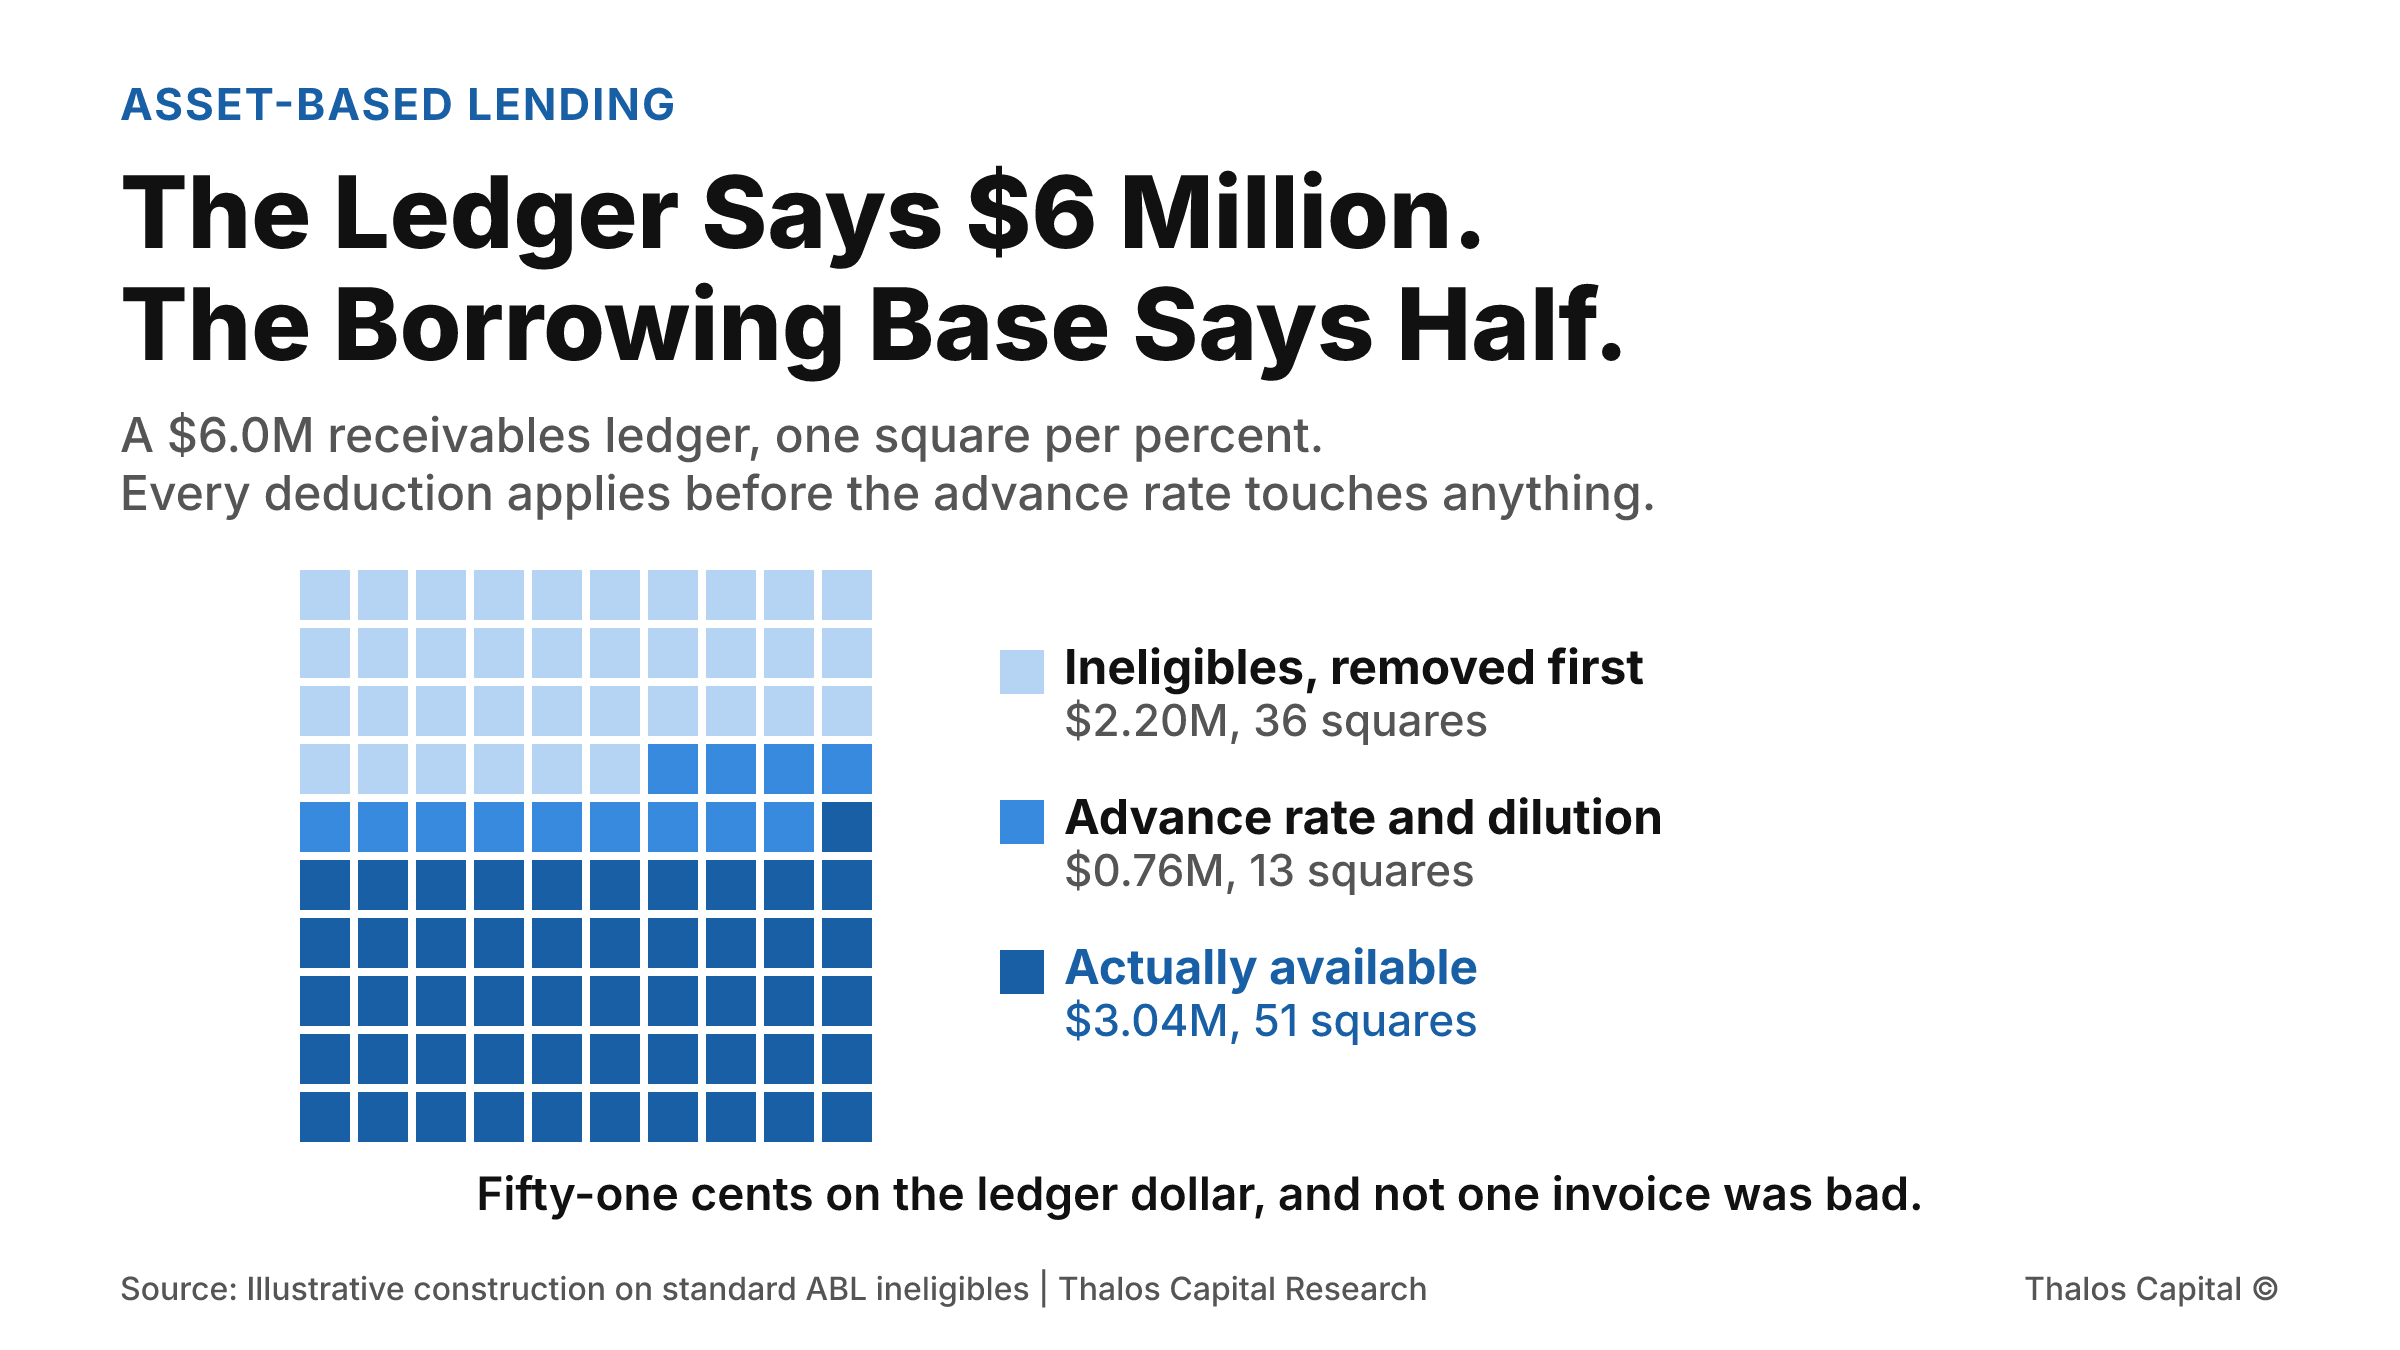
A hundred-square waffle of a $6 million receivables ledger showing 36 squares removed as ineligibles, 13 squares taken by the advance rate and dilution reserve, and 51 squares of actual availability at $3.04 million.

The Ledger Says $6 Million. The Borrowing Base Says Half.

Advance rate is the number every borrower asks about and the last one applied. Before it touches anything, the ineligibles come out, and on a $6 million receivables ledger they can remove $2.2 million without a single invoice being bad.
Read More
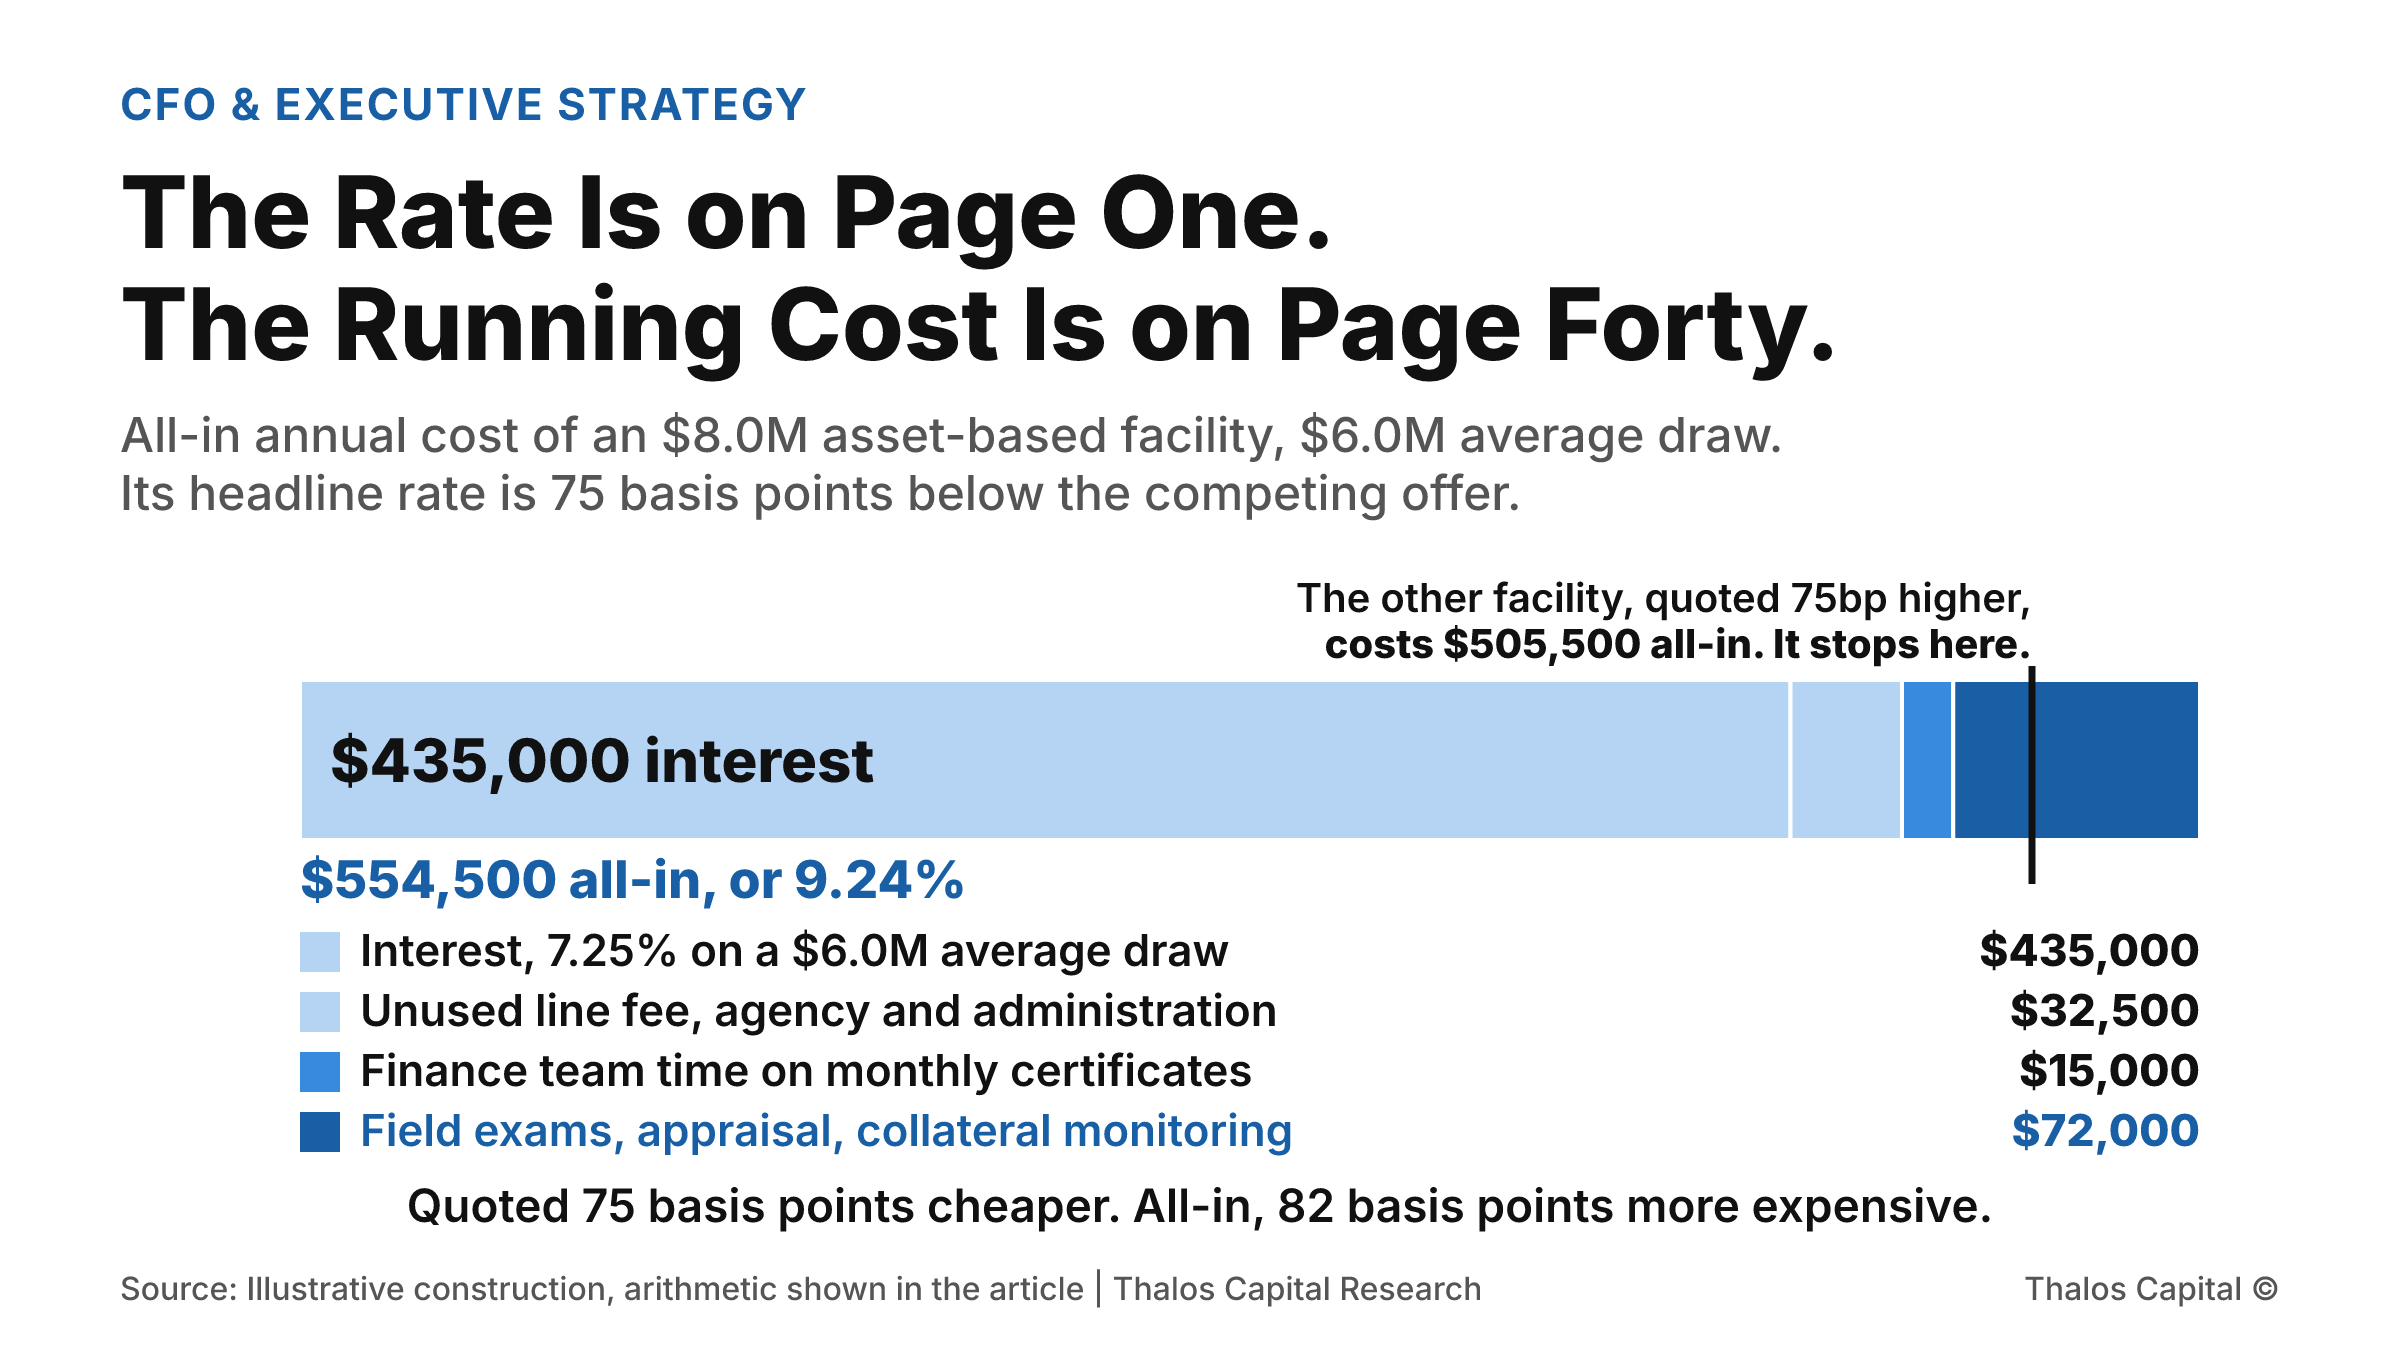
A single stacked bar of the all-in annual cost of an $8.0 million asset-based facility at a $6.0 million average draw, totalling $554,500, with a marker showing that a competing facility quoted 75 basis points higher costs $505,500 all-in.

The Rate Is on Page One. The Running Cost Is on Page Forty.

Two facilities quoted 75 basis points apart. Once field exams, appraisals, collateral monitoring and the finance team's own hours are counted, the cheaper-looking one costs 82 basis points more to run. The gap reverses entirely.
Read More
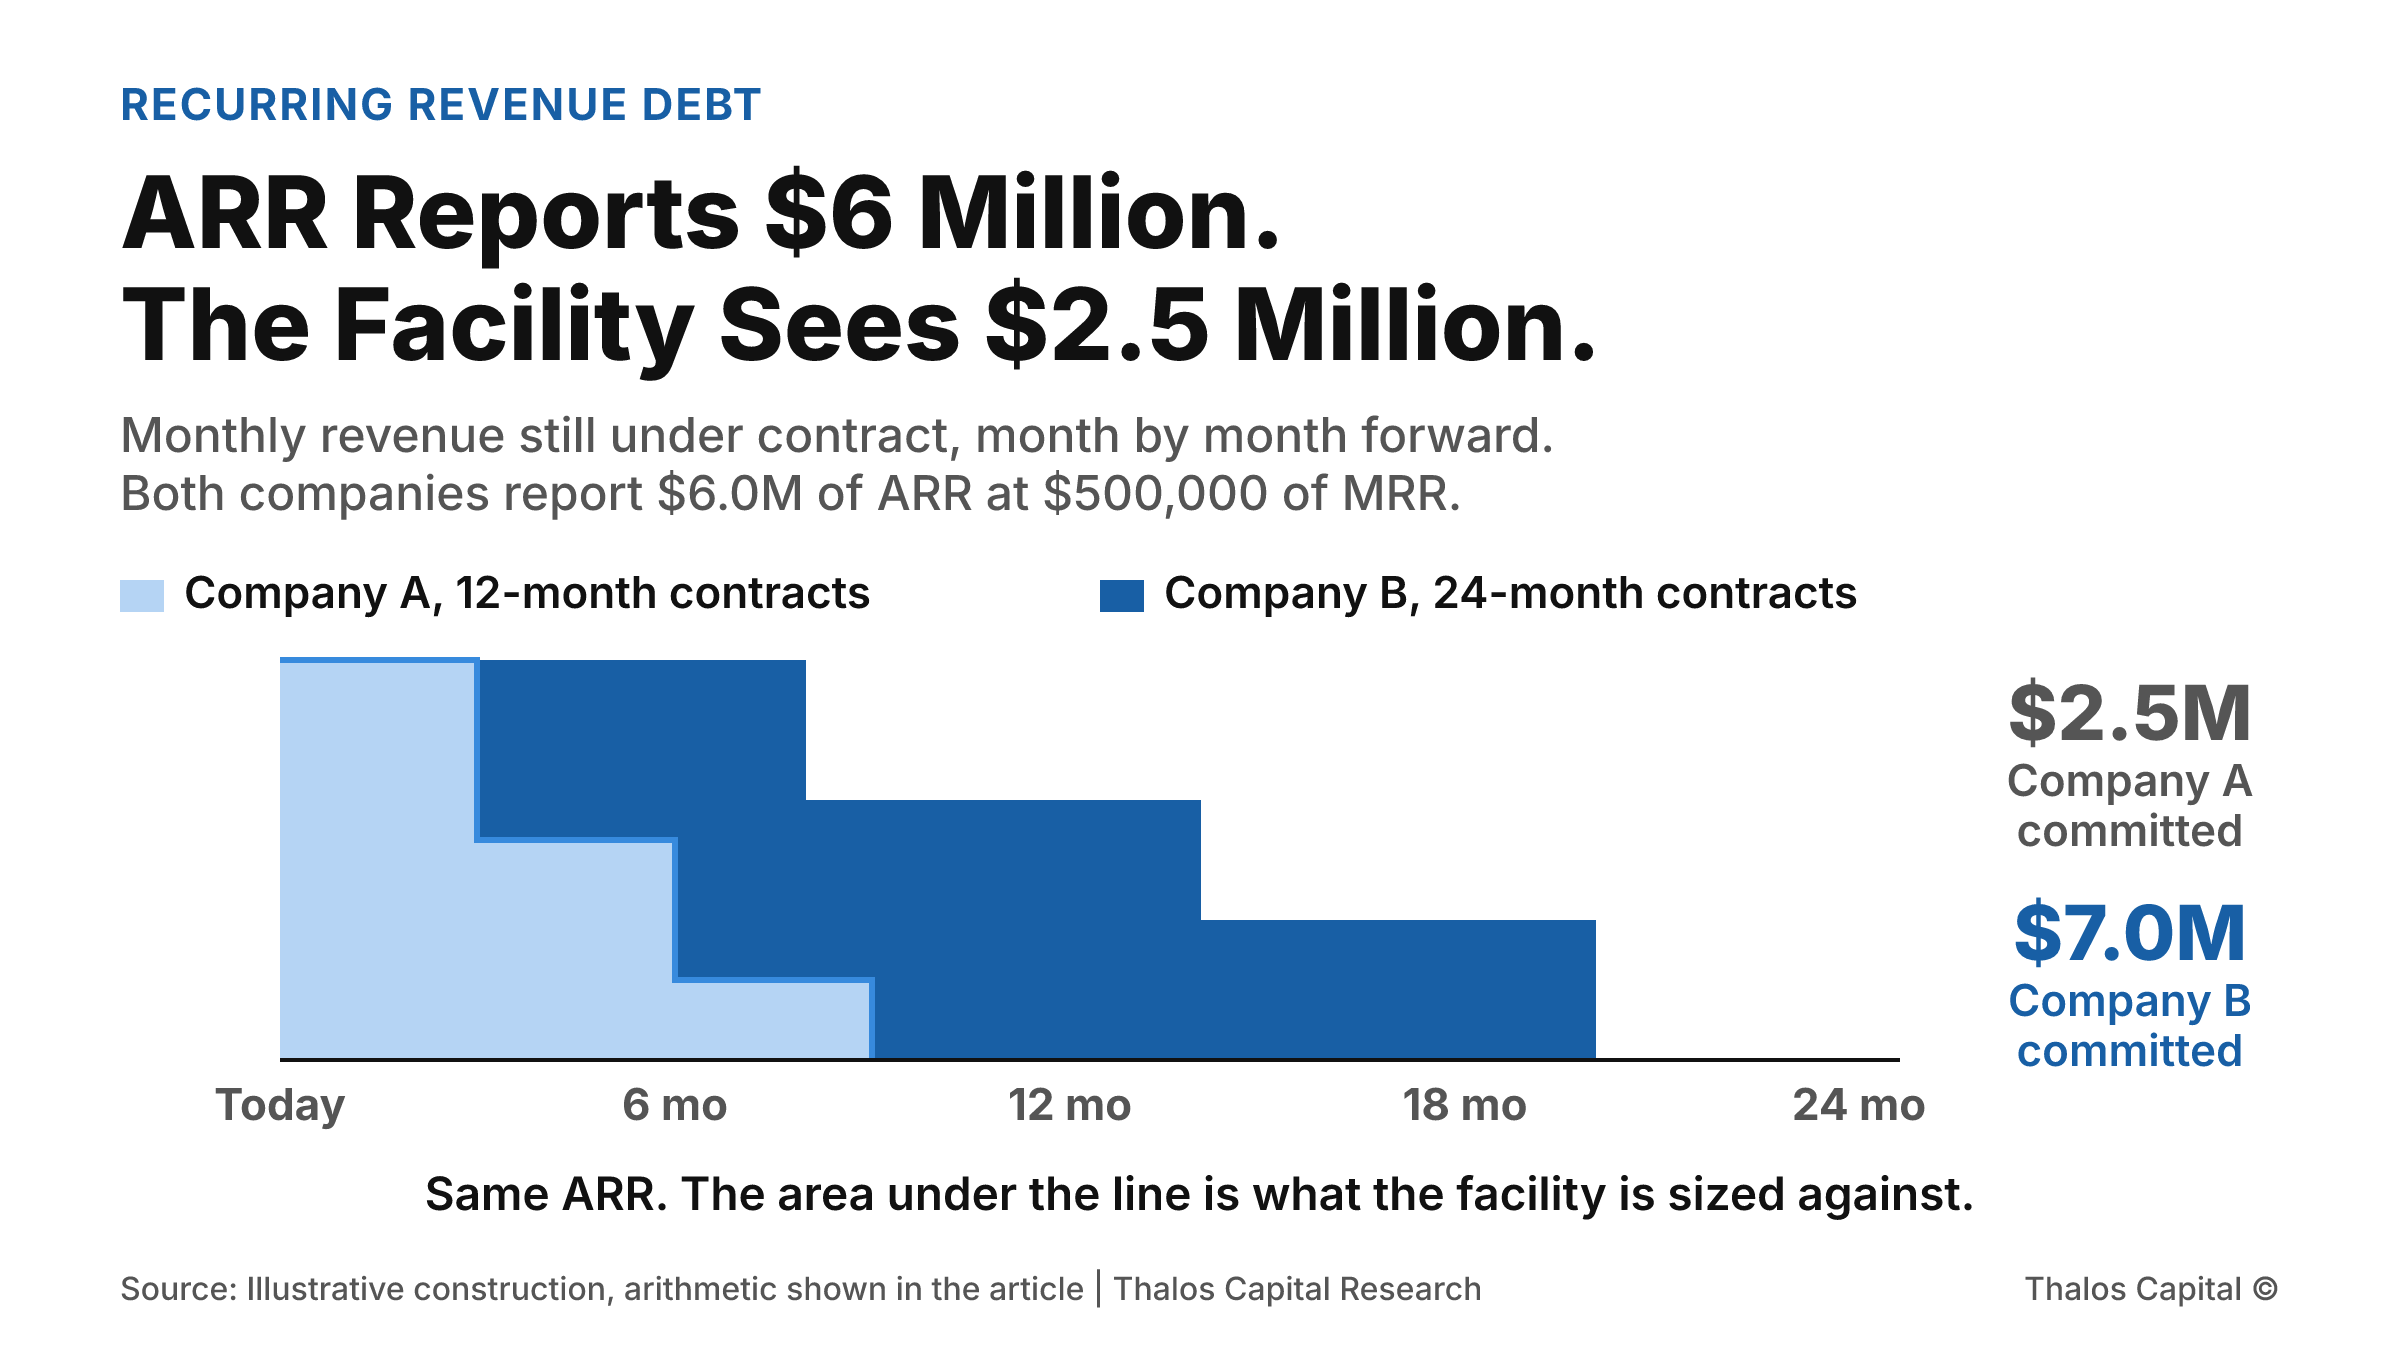
Two stepped areas showing monthly revenue still under contract over the next 24 months for two companies with identical $6.0 million ARR: a 12-month contract book holding $2.5 million of remaining contracted value and a 24-month contract book holding $7.0 million.

ARR Reports $6 Million. The Facility Sees $2.5 Million.

Two recurring-revenue companies each report $6.0 million of ARR. One is offered a $2.0 million facility and the other $1.0 million. The difference is contract length, and it does not appear in any metric either company reports.
Read More
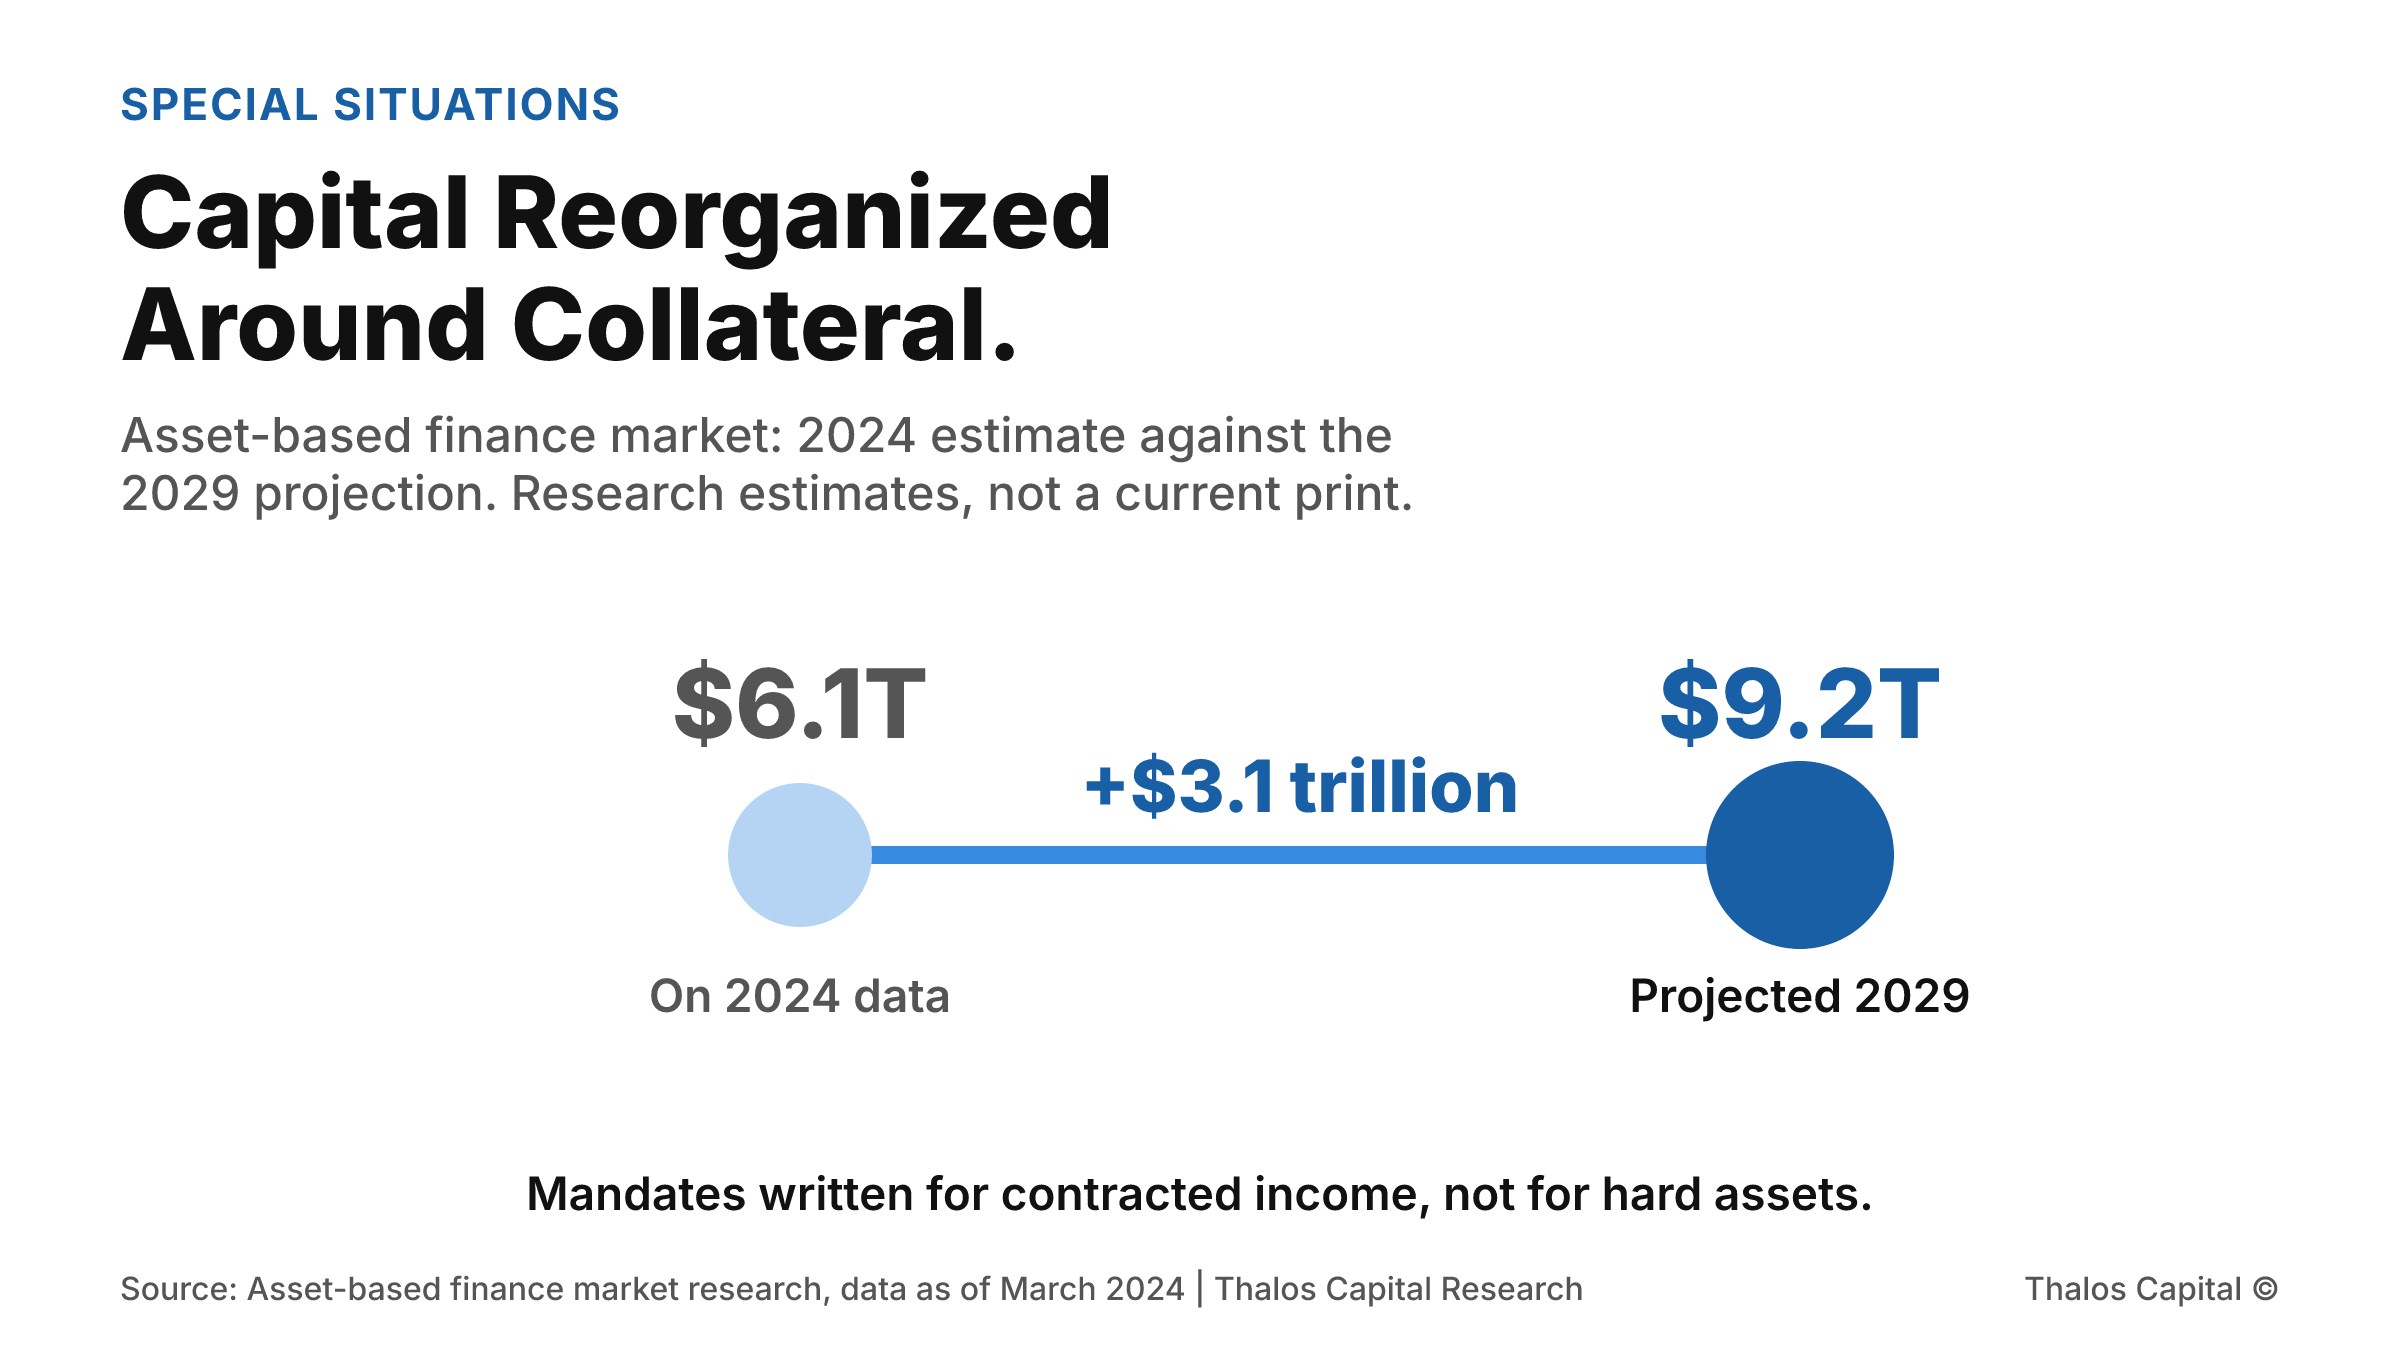
Two point range chart showing the asset-based finance market estimated at more than $6.1 trillion on 2024 data and projected to reach $9.2 trillion by 2029, an increase of roughly $3.1 trillion.

Capital Reorganized Around Collateral. Your Contracts Are Collateral.

Asset-based finance was estimated at more than $6.1 trillion on 2024 data and projected to reach $9.2 trillion by 2029. Inside it are mandates written for contracted and intangible cash flows rather than for hard assets.
Read More
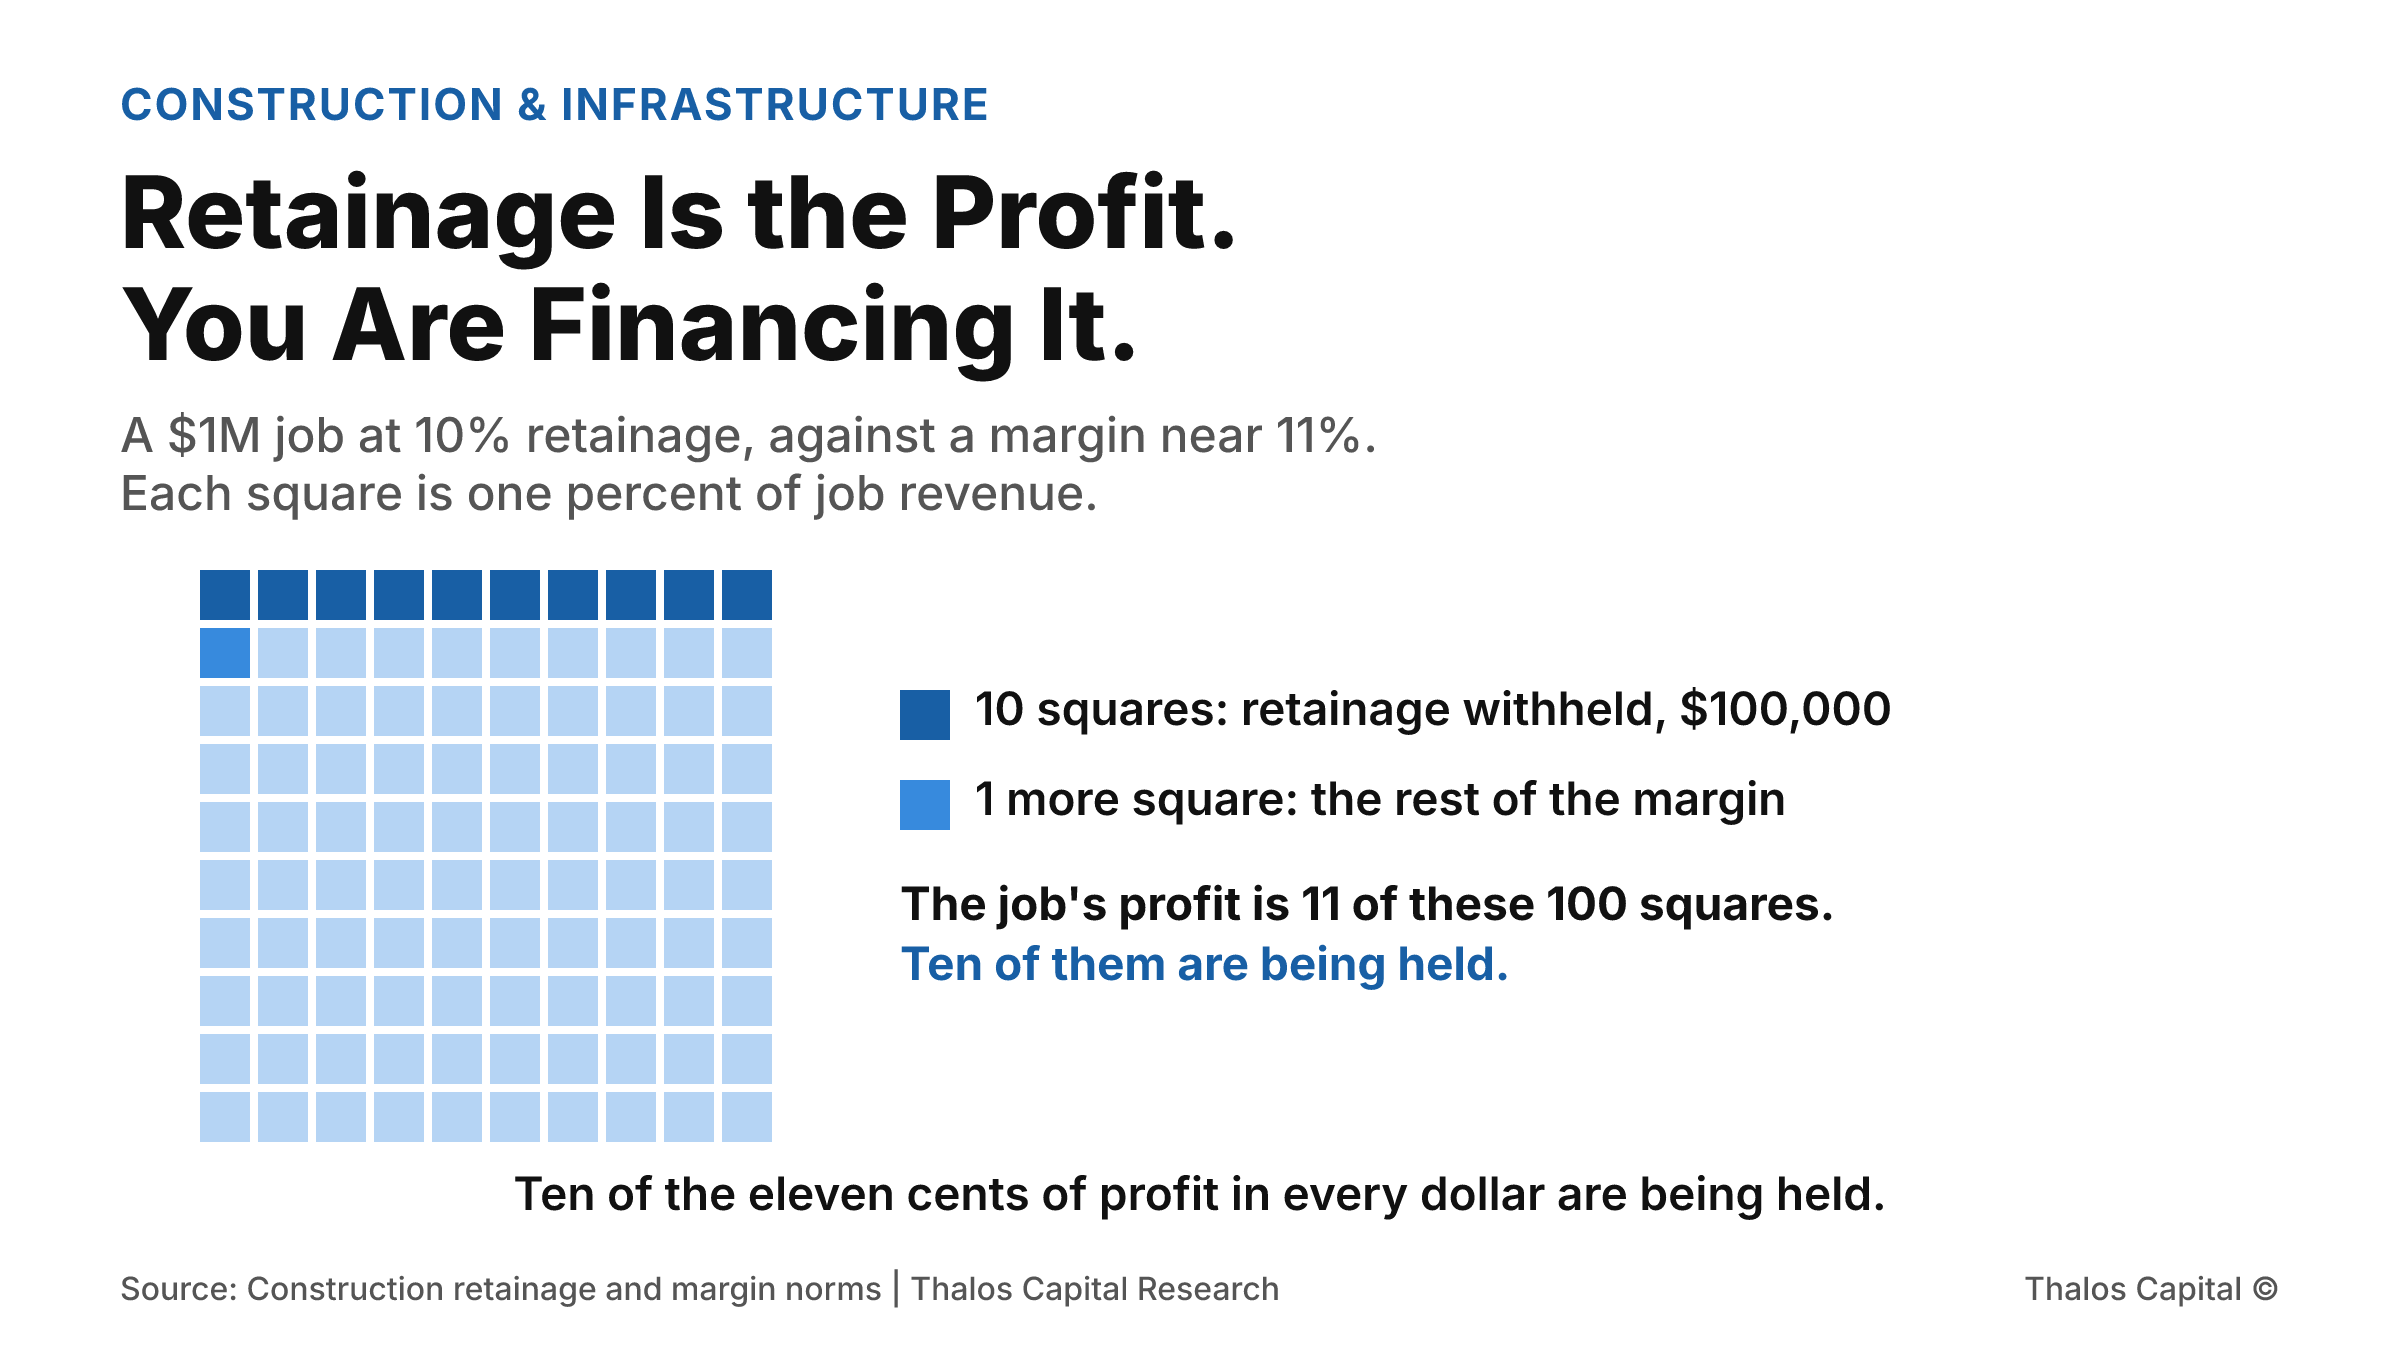
Waffle grid of 100 squares representing a $1 million job. Ten squares in dark navy show the $100,000 withheld as retainage and one further square in mid blue completes the roughly 11 percent margin, so ten of the eleven profit squares are being held.

Retainage Is the Profit. You Are Financing It.

A ten-month job billing $100,000 a month withholds $100,000 by closeout. At builder margins near 11 percent that is almost the entire profit on the job, and a standard receivables facility gives you nothing against it.
Read More
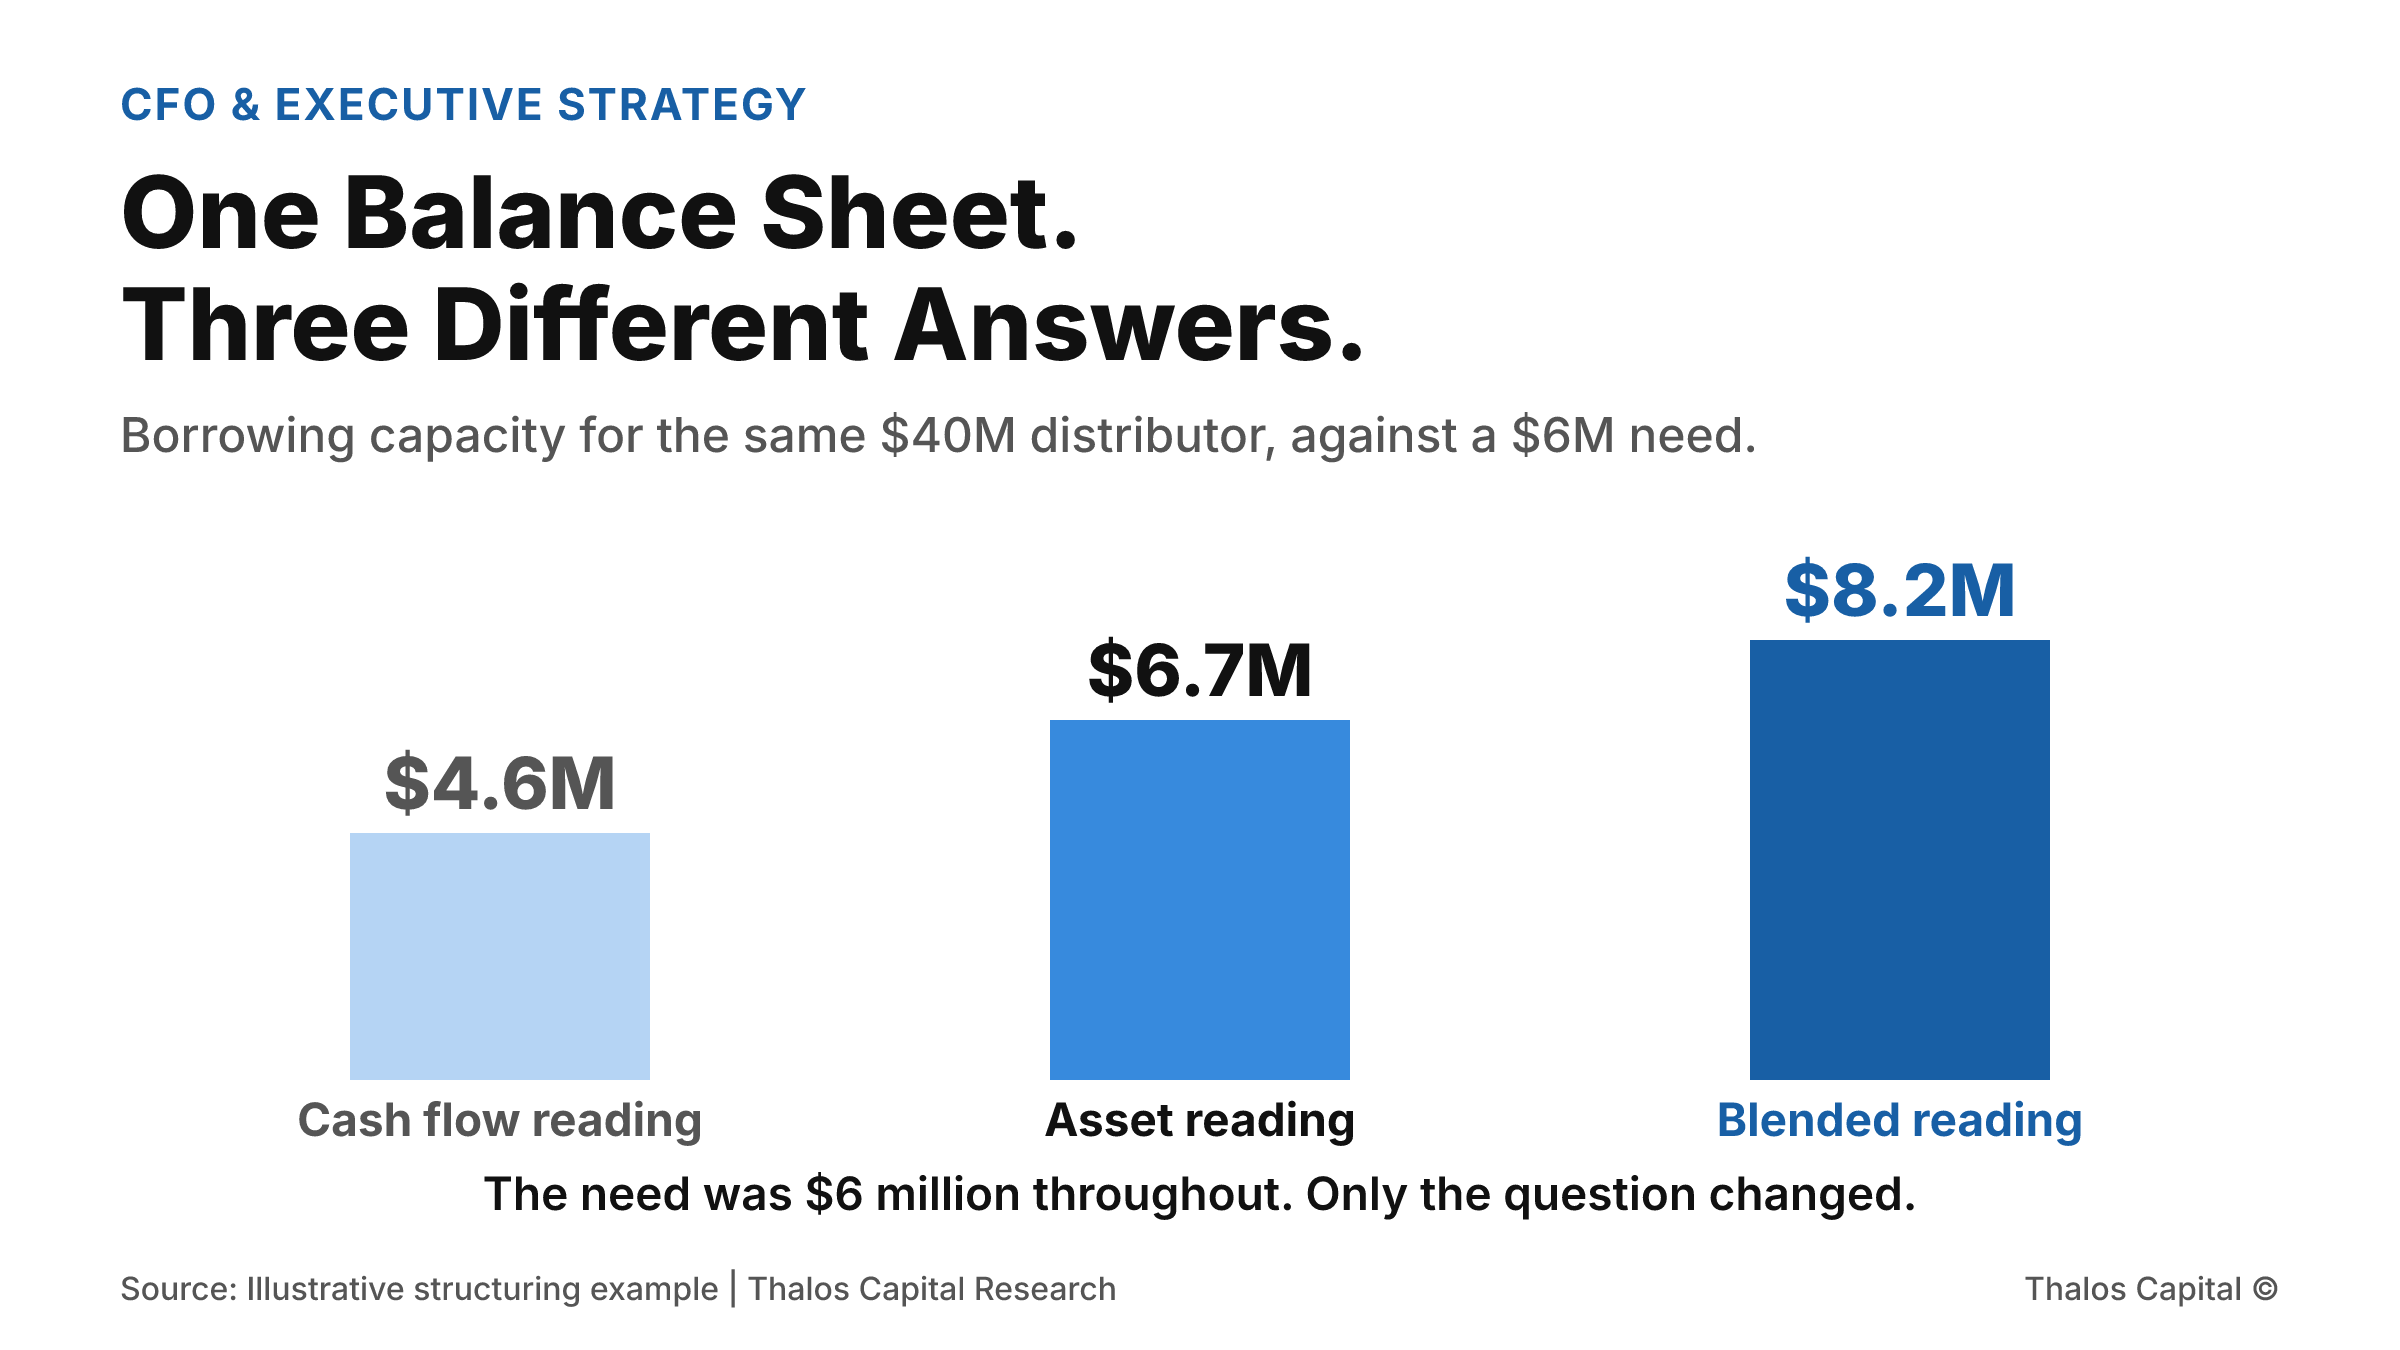
Column chart showing three borrowing capacity readings for the same distributor: $4.6 million on a cash flow reading, $6.7 million on an asset reading, and $8.2 million on a blended reading shown in the darkest navy, against a $6 million financing need.

One Balance Sheet. Three Different Answers.

A distributor doing $40 million in revenue needs $6 million. Read against cash flow it is short. Read against its assets it clears. Read as a blend it borrows $8.2 million. Same company, same week, three answers.
Read More
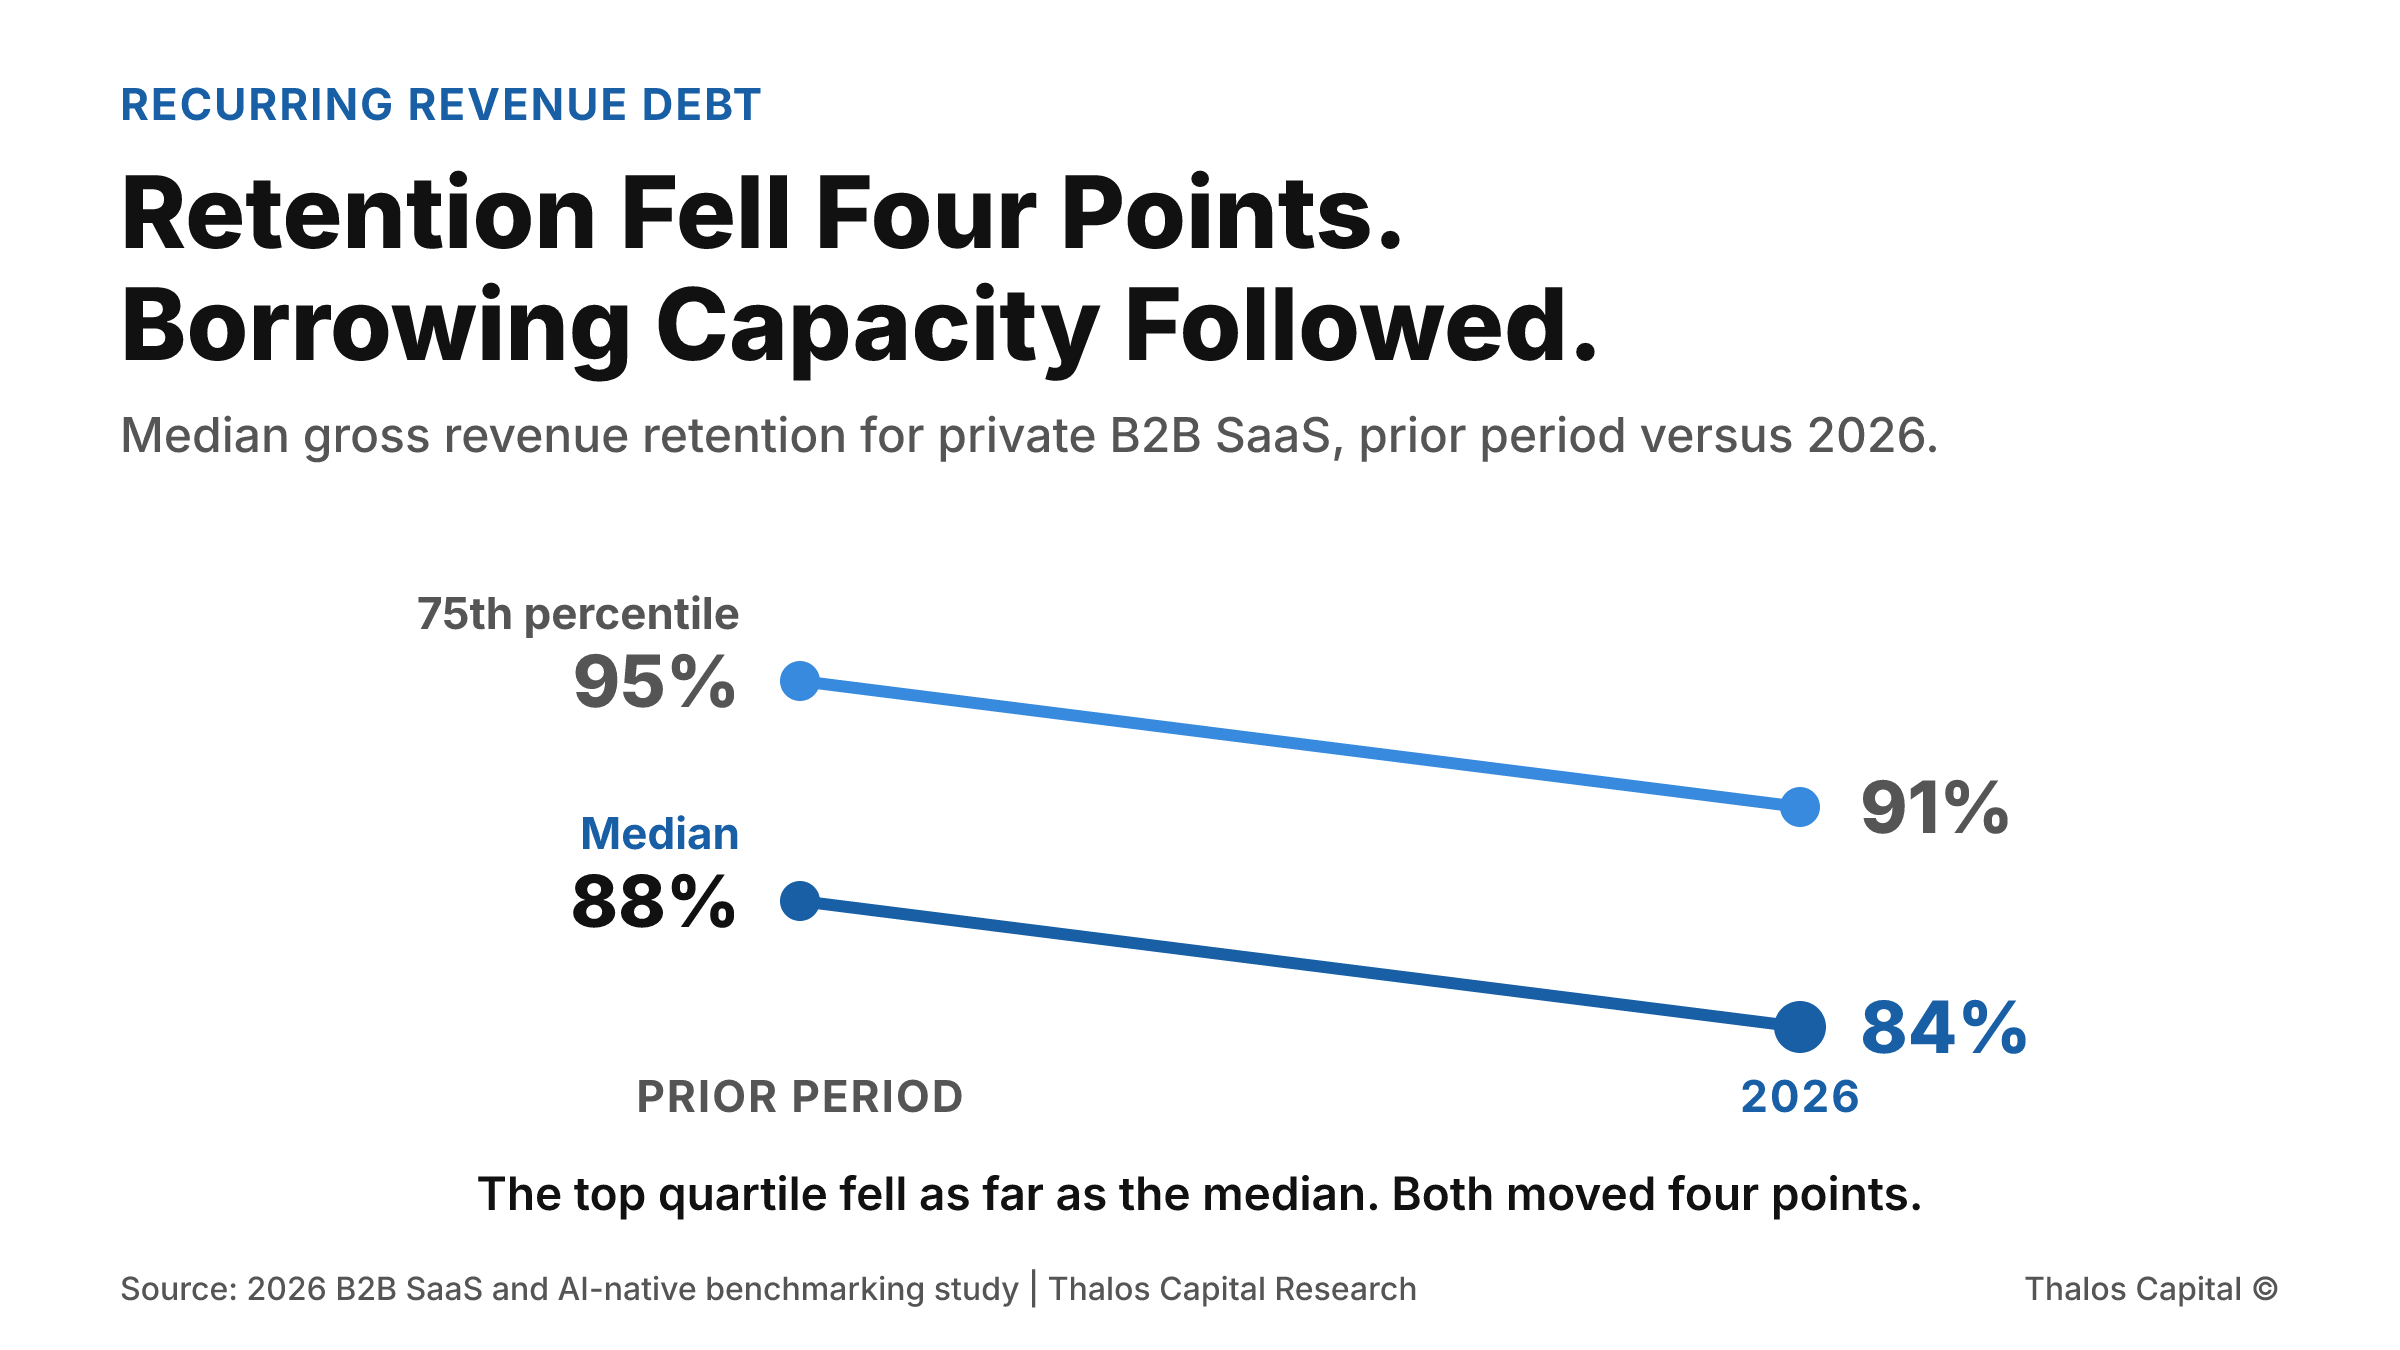
Slope chart comparing gross revenue retention for private B2B SaaS between the prior period and 2026, showing the median falling from 88 percent to 84 percent and the 75th percentile falling from 95 percent to 91 percent, both lines down four points.

Retention Fell Four Points. Your Borrowing Capacity Followed.

Median gross revenue retention for private B2B SaaS fell from 88 to 84 percent in 2026, and the top quartile fell just as far. For a company planning to borrow against contracted revenue, that four point move is a borrowing base question.
Read More
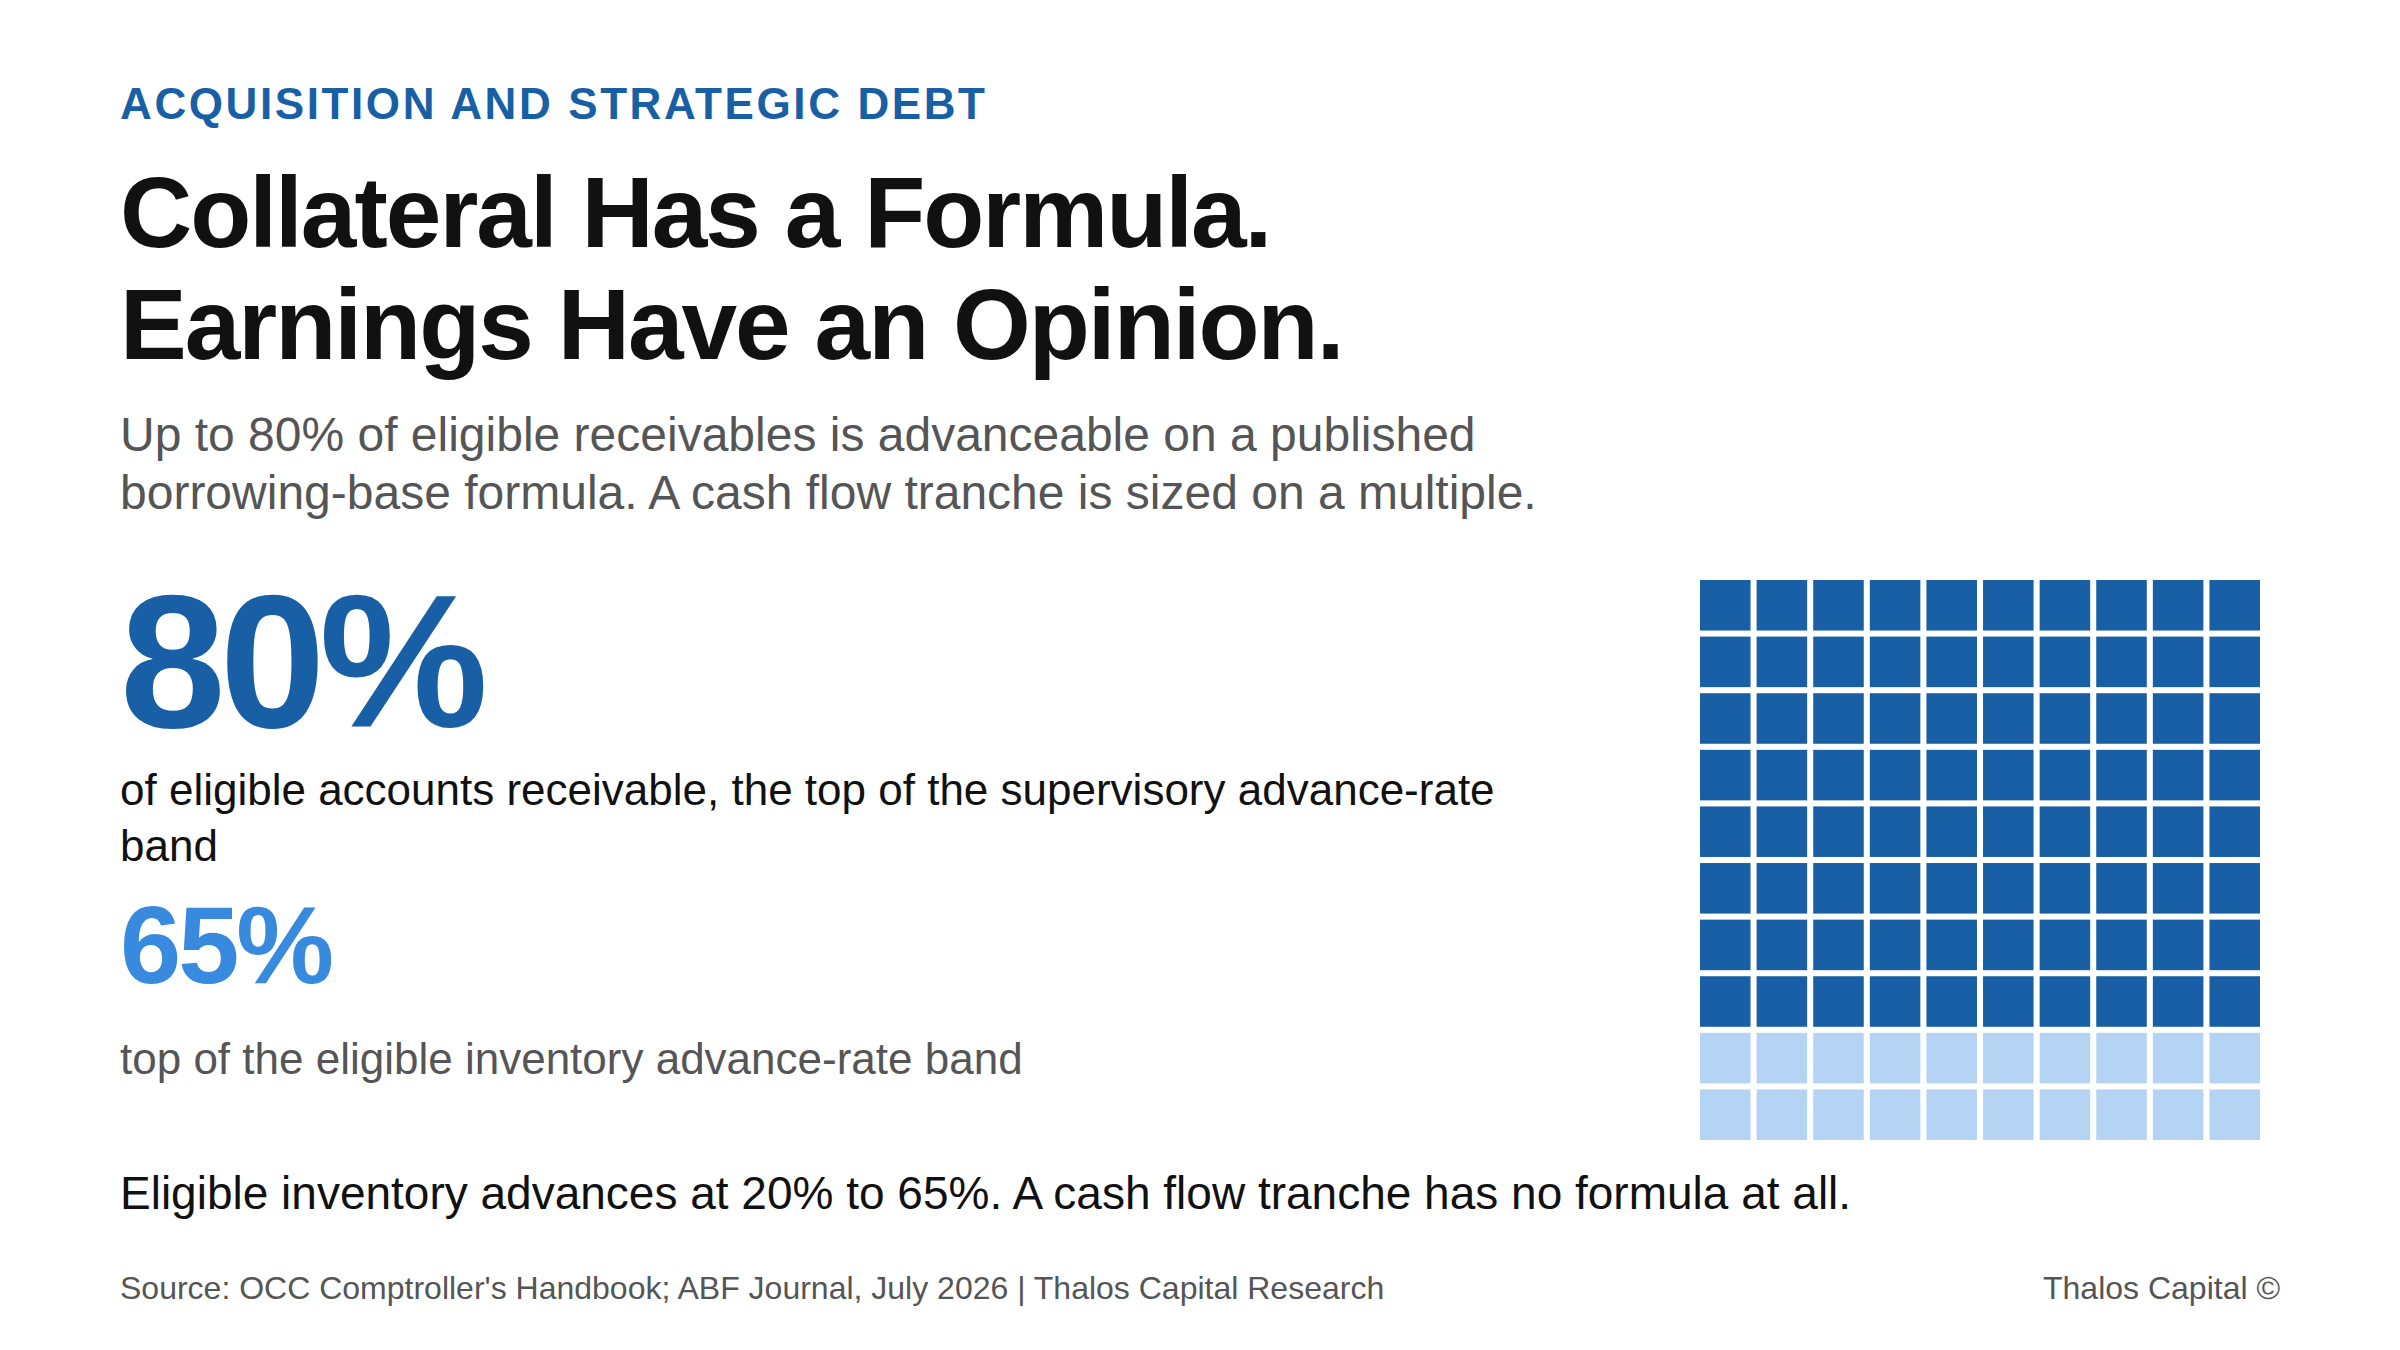
Squares pictogram showing 80 of 100 filled, representing the top of the 70 to 80 percent advance-rate band on eligible accounts receivable under a borrowing-base formula, with the 65 percent eligible inventory ceiling shown alongside.

You Are Buying a Balance Sheet and Financing It Like a Cash Flow Statement

Two facilities priced 200 to 250 basis points apart in the same week. The difference was collateral, not credit. Why acquisition debt sized only on EBITDA leaves both pricing and capacity on the table.
Read More
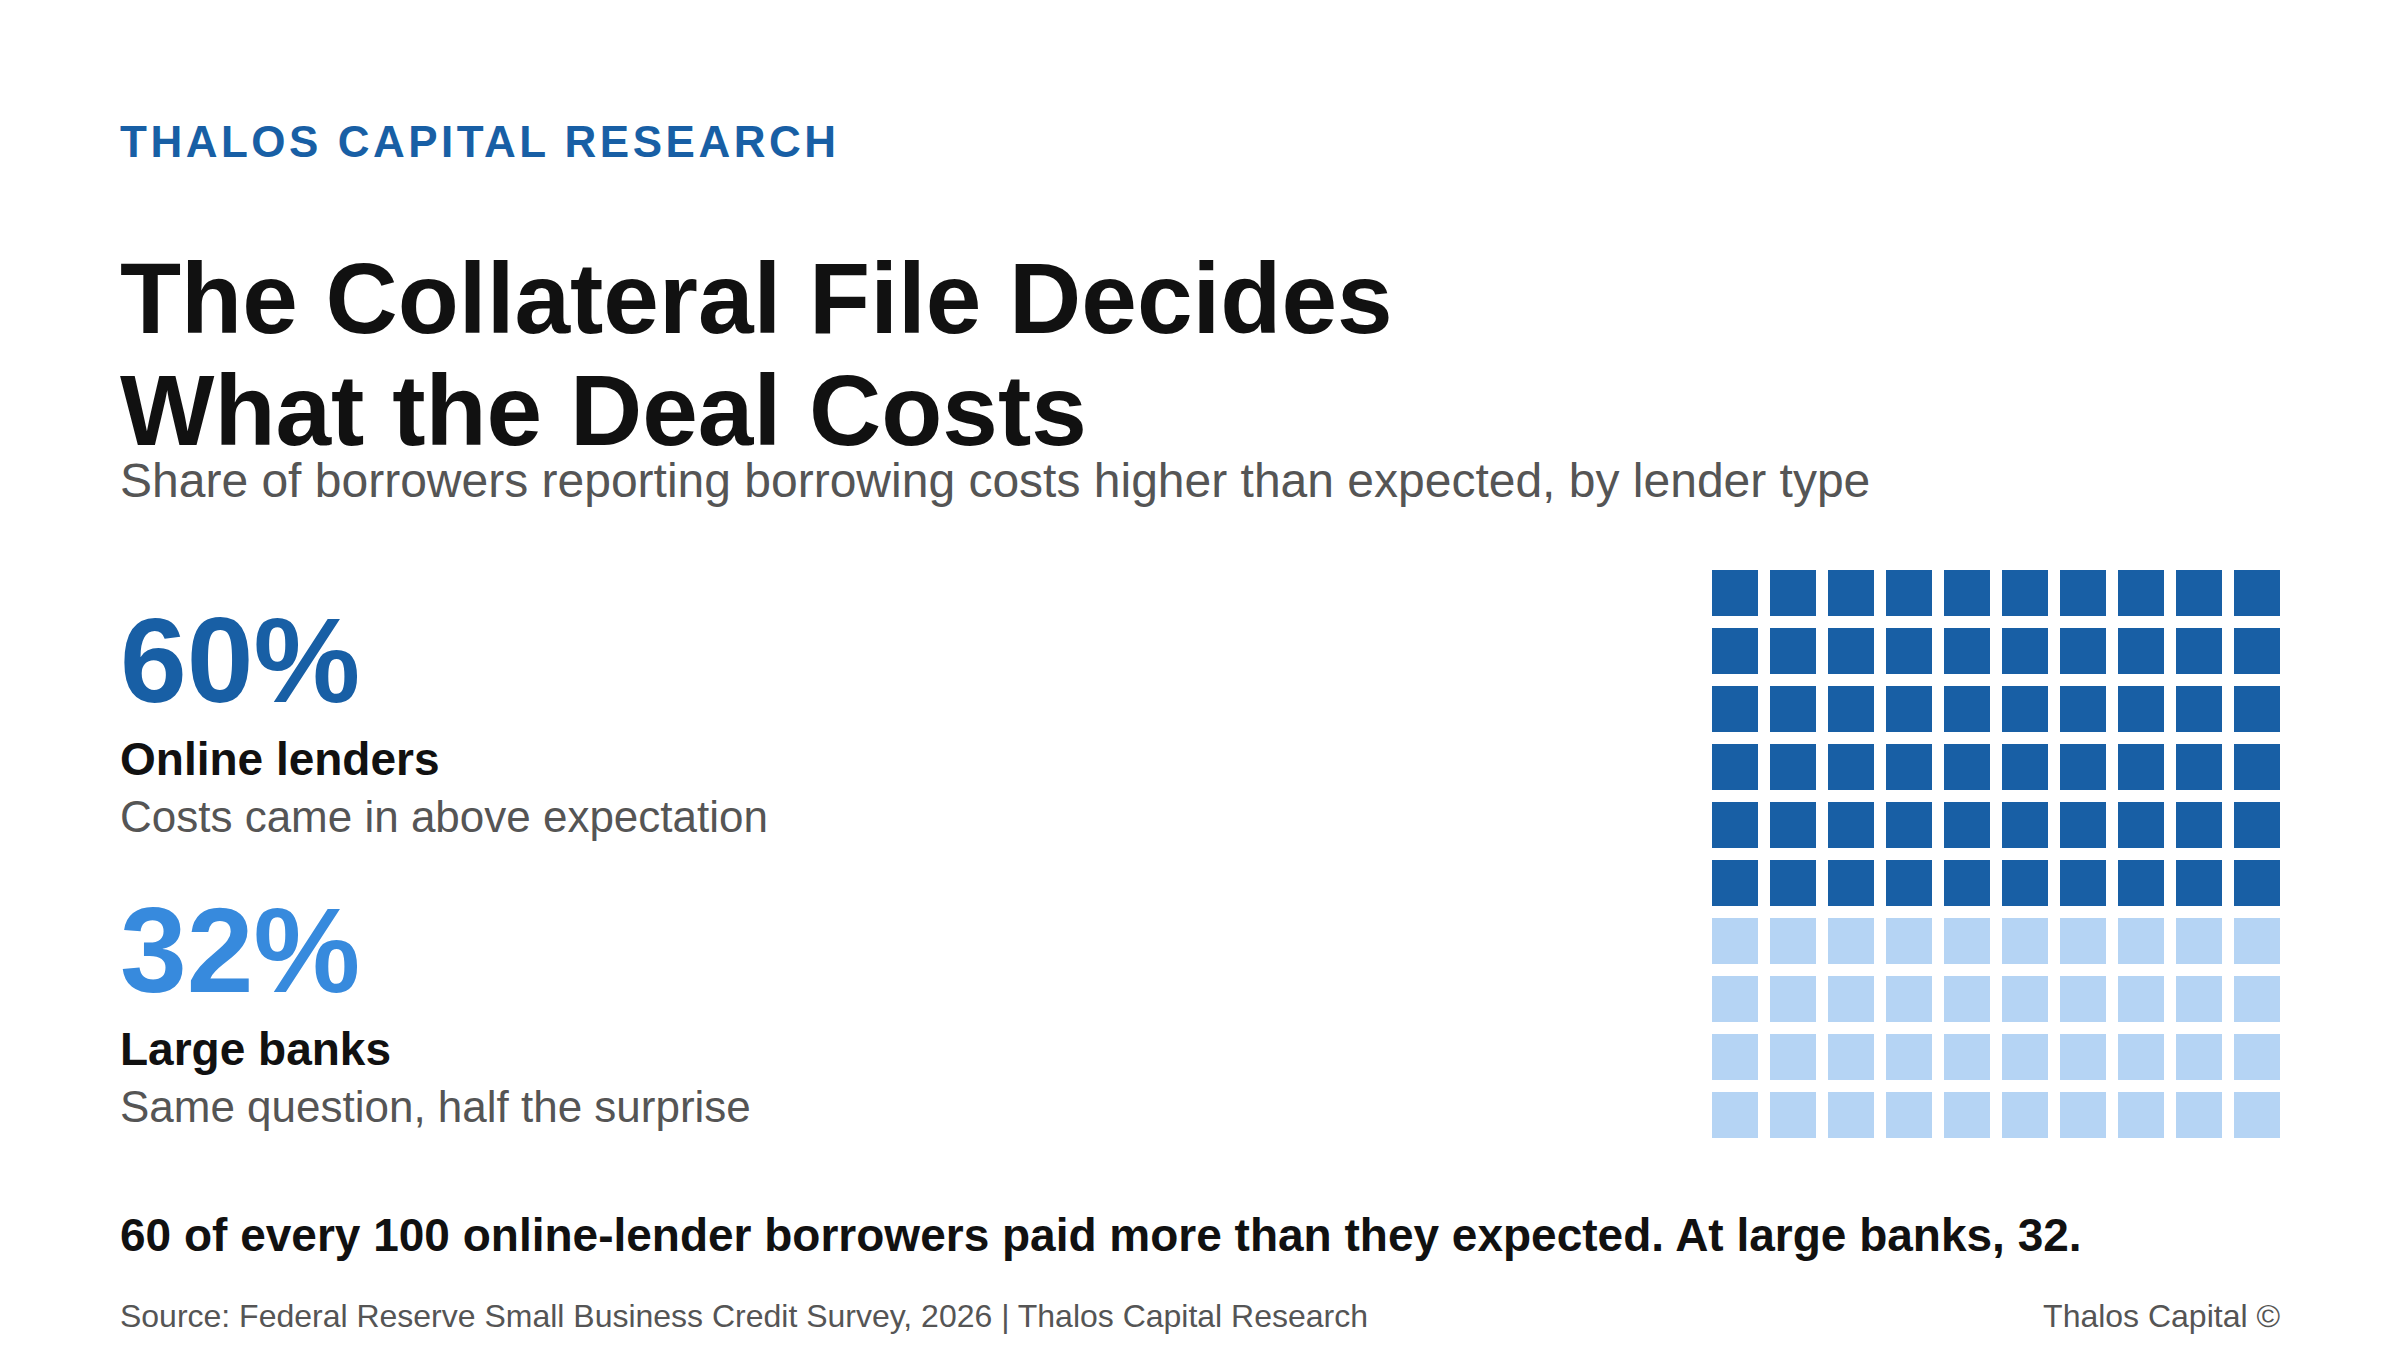
Waffle chart showing 60 of 100 squares in dark navy, representing the 60 percent of online-lender borrowers who reported borrowing costs higher than expected, compared with 32 percent at large banks.

Collateral Verification Is Now the First Diligence Question, Not the Last

Sixty percent of online-lender borrowers paid more than they expected. The gap is not about lender type. It is about what the borrower verified before the process started.
Read More
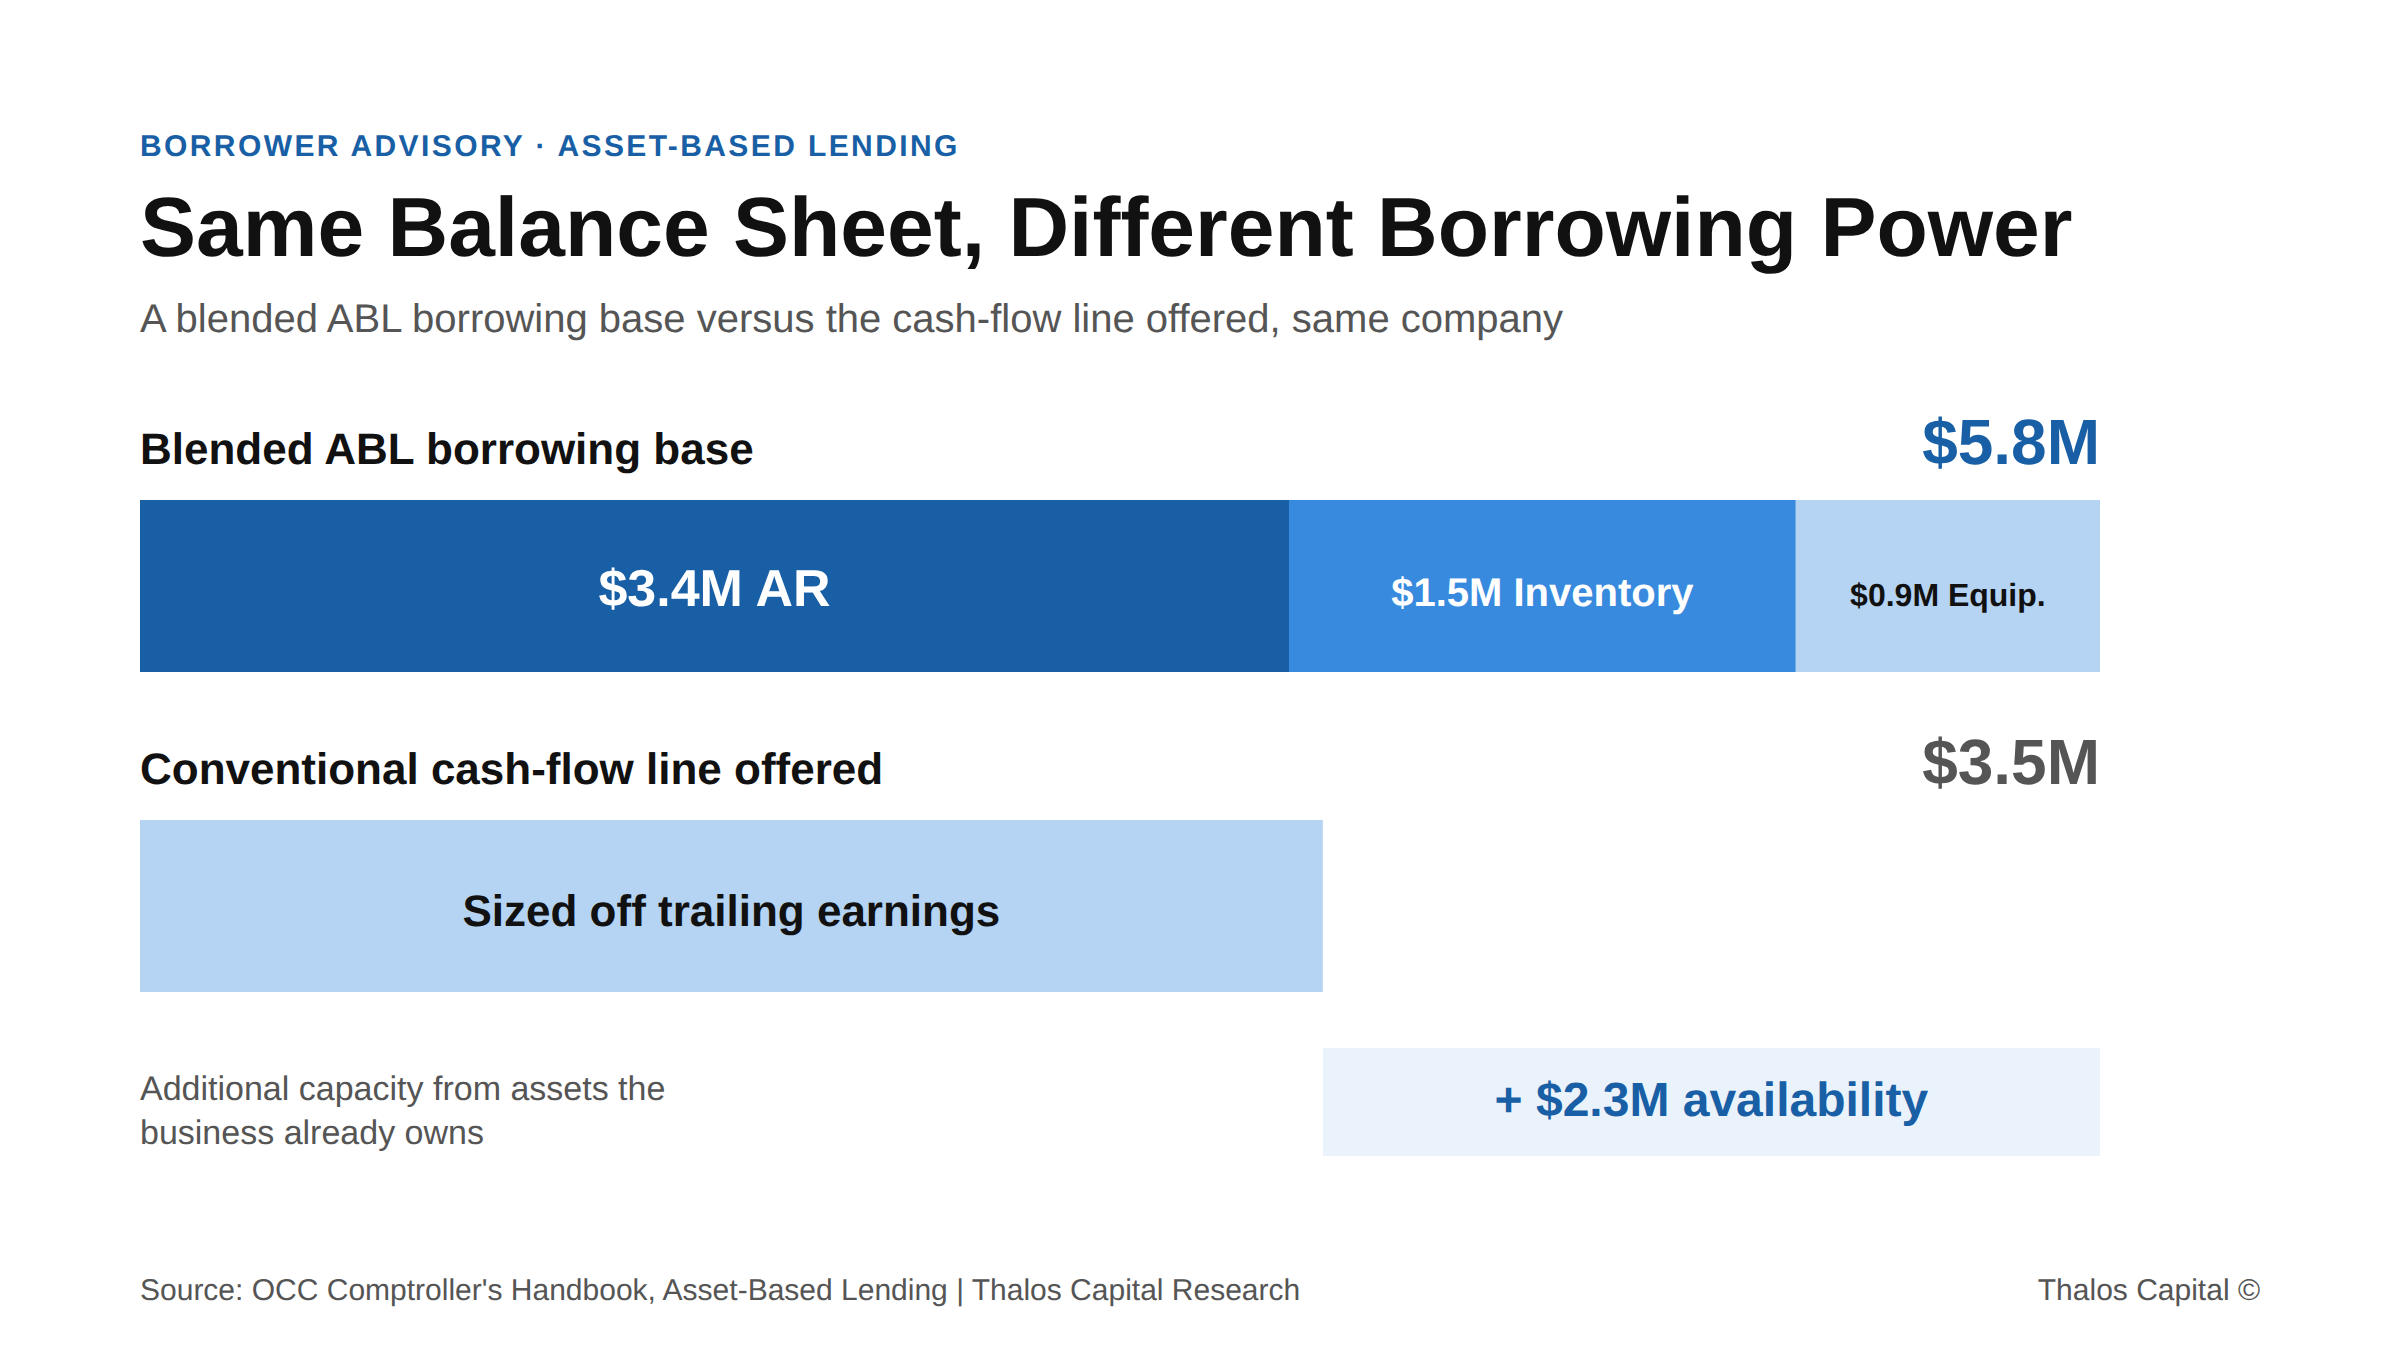
Single stacked bar. how a blended borrowing base is built, against the cash-flow line offered.

Asset-Rich, Credit-Capped: Why Tightening Operators Borrow Against the Wrong Thing

Asset-rich operators tightening through rising costs often borrow against the wrong thing. Why a cash-flow line caps capacity the balance sheet could exceed, with the numbers.
Read More
Working through a financing decision?
Insights are a starting point. A conversation maps your actual options.
Tell us what you are financing and we will map the structures and sources that fit.
Submit your financing request →
Explore our financing solutions
Equipment FinancingWorking CapitalAsset-Based LendingStrategic Debt